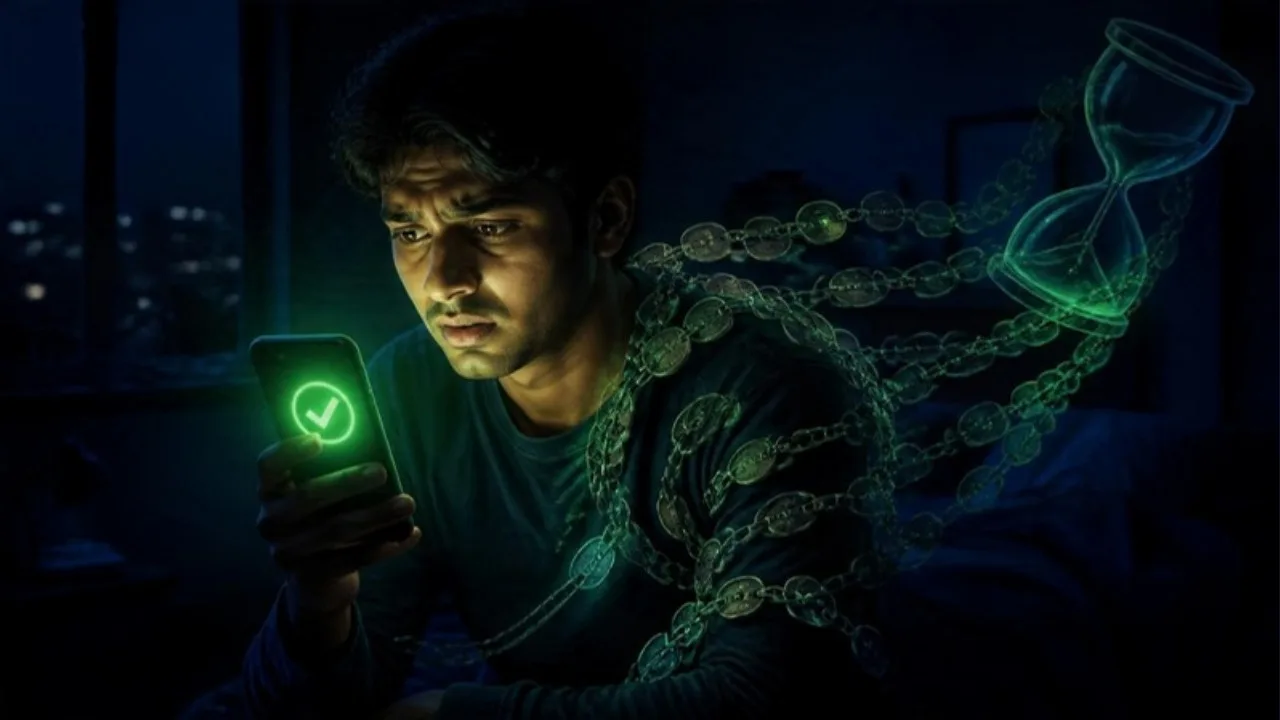
Instant loan offers work less by their interest rate and more by urgency: they arrive at the moment of financial stress and shrink hesitation. The danger is not the first loan but the cycle of top-ups and refinancing that follows, which quietly sells your future income. This article explains the psychology and how to protect yourself.
How instant digital credit is turning financial anxiety into a new generation debt trap.
A phone rings. “Sir, you are eligible for ₹3 lakh immediately.”
There is no branch visit. No long conversation. No waiting for documents. No uncomfortable questions about why the money is needed. Within minutes, money can appear in the bank account.
For a person struggling with school fees, medical expenses, rent, an EMI, a wedding, a family emergency or simply the rising cost of living, the offer can feel less like a loan and more like rescue. And this is where the real psychological story begins.
Digital lending has brought extraordinary speed and convenience to India’s financial system. Technology can analyse data, assess creditworthiness and deliver credit much faster than traditional processes. But the same technology can also make borrowing psychologically easier than thinking about borrowing.
The danger is not necessarily the first loan. The danger is the psychological journey that begins after the first loan.
India may therefore be facing a new form of financial vulnerability—not necessarily a banking crisis in the traditional sense, but a silent household debt crisis, in which millions of individuals continuously refinance, top-up, consolidate and roll over obligations without fully understanding how much of their future income has already been sold.
RBI itself has identified concerns around digital lending including mis-selling, unfair business conduct, exorbitant pricing and unethical recovery practices, and its Digital Lending Directions, 2025 were designed partly to address these risks.
Key Takeaways
- Urgency sells, not the rate. Messages like “pre-approved” and “offer valid today” are built to reduce hesitation, so you ask “How much can I get?” instead of “Should I borrow?”
- Eligibility is not affordability. A lender’s willingness to lend is no proof that you should borrow; count all your EMIs together and compare total cost and APR.
- Pause before you press Accept. Ten minutes and ten honest questions can break the refinancing cycle that sells tomorrow’s income today.
Table of Contents
- The most powerful selling point of instant loan offers is not the interest rate—it is urgency
- Pre-approved credit creates the illusion of free money
- The first psychological hit: “I have an emergency solution”
- “Limited-period offer” attacks the fear of missing out
- The “future top-up” promise creates a dangerous mental bridge
- The EMI illusion
- Processing fee is psychologically smaller than interest
- The most dangerous stage begins after disbursement
- Debt can become a lifestyle rather than an emergency tool
- The “repayment track” can become a psychological trap
- Debt consolidation can sometimes hide the underlying problem
- The post-disbursement psychology of “sunk cost”
- Then comes the refinancing cycle
- The phone has become both the wallet and the salesman
- The borrower may be financially stressed but digitally overconfident
- The greatest generational danger: selling tomorrow’s income today
- What happens to the next generation?
- The invisible crisis is not necessarily a banking crisis
- The lender also has a responsibility
- What should change?
- A new borrower-protection model
- What every borrower should do before pressing “Accept”
- A simple rule for the new generation
- From instant credit to intelligent credit
- The final question
1. The most powerful selling point of instant loan offers is not the interest rate—it is urgency
Traditional borrowing once created friction. A customer had to visit a branch, meet a banker, submit documents, wait for appraisal and perhaps answer uncomfortable questions: Why do you need this money? Digital lending has removed much of that friction.
Today, a customer may receive: “Pre-approved loan available.” “Special offer valid today.” “You are eligible for ₹5 lakh.” “Instant approval.” “No documentation.” “Increase your eligibility with timely repayment.”
Each sentence is technically a financial message. But psychologically, it is something more powerful: a message designed to reduce hesitation. The customer is not necessarily thinking, “Should I borrow?” Instead, the mind begins thinking, “How much can I get?” That is a fundamental change.
2. Pre-approved credit creates the illusion of free money
A pre-approved loan can psychologically feel different from a normal loan. The customer may unconsciously interpret it as: “The bank knows me, so I must be financially trustworthy.” But eligibility is not the same as affordability. A person may be eligible for ₹5 lakh and still be unable to comfortably repay ₹5 lakh.
The distinction is critical. Credit eligibility asks: “Can we lend?” Financial affordability asks: “Can you repay without damaging your life?” These are not the same question. The danger becomes greater when customers mistake the lender’s willingness to lend for evidence that they should borrow.
3. The first psychological hit: “I have an emergency solution”
Financial stress narrows human thinking. When a person urgently needs ₹50,000, ₹1 lakh or ₹3 lakh, the mind tends to focus on the immediate problem. The future EMI becomes psychologically distant. This is a classic behavioural pattern: immediate pain defeats future caution.
Suppose someone needs ₹1 lakh today. The mind sees ₹1,00,000 received today. It does not naturally feel ₹1,00,000 + interest + processing fee + taxes/other disclosed charges + months of future EMIs. The loan therefore solves today’s problem by creating tomorrow’s obligation.
This is not necessarily irrational behaviour. It is often financial stress making the decision for the borrower.
4. “Limited-period offer” attacks the fear of missing out
Financial marketing increasingly uses psychological triggers familiar from shopping platforms: “Offer expires today.” “Special rate for selected customers.” “Pre-approved limit available only for a limited period.” The customer begins experiencing FOMO—fear of missing out.
But borrowing is not shopping. If a person does not purchase a television today, the opportunity may disappear. If a person does not borrow today, there should ideally be no psychological feeling that he has lost something valuable. Yet marketing can make available credit feel like an opportunity that must be captured.
The customer begins asking, “Why should I lose this opportunity?” instead of “Why should I take this liability?” That change in question can alter financial behaviour dramatically.
5. The “future top-up” promise creates a dangerous mental bridge
One of the most powerful psychological attractions is the possibility of future credit. The customer hears: “Maintain a good repayment track and your eligibility may increase.” This sounds responsible. But it can unintentionally create a different mental association: Repayment → more borrowing capacity.
Normally, repayment should mean: Debt → Debt reduction → Financial freedom. But the borrower may learn: Debt → Good repayment → Higher limit → More debt. This transforms responsible repayment into a pathway toward additional borrowing. The danger is particularly high among young earners whose income is rising but whose financial discipline is still developing.
6. The EMI illusion
EMI is one of the most psychologically powerful inventions in modern consumer finance. A ₹3 lakh loan can sound frightening. But “Only ₹9,999 per month” sounds manageable. The human brain is much better at understanding today’s monthly cash flow than a multi-year total financial commitment.
This is why borrowers should never evaluate a loan only by EMI. They should ask: What is the total amount I will repay? If a ₹3 lakh loan eventually requires ₹3.75 lakh or ₹4 lakh to repay, that difference is the real cost of borrowing—not merely the EMI.
RBI’s KFS framework is specifically intended to make key loan information and the all-inclusive cost easier to understand before the borrower commits.
7. Processing fee is psychologically smaller than interest
A borrower may react strongly to “Interest rate: 24%.” But may not pay the same attention to a processing fee of ₹6,000, a documentation fee of ₹1,000, a verification charge, insurance and other disclosed charges. The customer sees multiple small numbers instead of one large cost.
That is why APR—the annualised cost of credit including applicable charges—is far more meaningful than looking at the headline interest rate alone. RBI’s digital lending framework requires regulated entities to disclose APR and provide a Key Fact Statement (KFS), with charges forming part of the required disclosure framework.
The consumer lesson is simple: never compare loans only by interest rate. Compare their total cost.
8. The most dangerous stage begins after disbursement
Before disbursement, the customer feels relief. After disbursement, the money is spent. Then the EMI begins. At this stage, the psychology changes from “I need money” to “I need money again.”
Suppose a person earns ₹50,000 per month. Existing EMI: ₹12,000. New EMI: ₹8,000. Credit-card payment: ₹5,000. The person’s disposable income has quietly fallen by ₹25,000. Nothing dramatic happened on the day the loan was sanctioned. But a large portion of the person’s future salary has already been committed.
9. Debt can become a lifestyle rather than an emergency tool
This is where the greatest generational danger lies. The first loan may be for medical expenses, education, home repair or a genuine family emergency. The second may be for a smartphone, travel, lifestyle purchases or wedding expenditure.
The third may be used to repay the first. Then a top-up may be used to repay the second. Eventually, the borrower is no longer borrowing for a specific productive purpose. Borrowing itself becomes part of household cash-flow management. That is the beginning of debt dependency.
10. The “repayment track” can become a psychological trap
There is a legitimate financial reason for rewarding good repayment behaviour. But customers may psychologically interpret it differently. They may think: “I have paid every EMI on time, so I can safely take another loan.” This is dangerous.
A good credit history means the borrower has demonstrated repayment behaviour. It does not mean that additional borrowing is financially advisable. The most dangerous borrower is not necessarily someone who defaults. It may be the person who never defaults but continuously increases his debt.
11. Debt consolidation can sometimes hide the underlying problem
Imagine someone has a credit-card outstanding of ₹70,000, a personal loan of ₹1.5 lakh and a consumer loan of ₹60,000. A new lender offers: “Take ₹3 lakh and consolidate everything into one EMI.” Mathematically, this may sometimes be sensible.
But psychologically, something else can happen. The old liabilities disappear. The borrower feels financially clean. Then, after several months, the credit card becomes available again. The borrower starts spending again. Now the person has a new consolidated loan + new credit-card debt.
Debt consolidation solves the symptom only when the underlying spending behaviour remains unchanged.
12. The post-disbursement psychology of “sunk cost”
Once a person has borrowed, cancelling the decision feels difficult. The borrower thinks: “The money is already spent.” “I have already paid several EMIs.” “I will manage somehow.” This is the psychology of sunk cost.
Instead of reconsidering the financial structure, the person continues. The result can be a slow transition from manageable debt to chronic debt.
13. Then comes the refinancing cycle
The borrower misses or struggles with an EMI. Another offer arrives: “Fresh loan available.” “Balance transfer.” “Top-up available.” “Instant cash.” The new loan temporarily reduces the pressure. But if the borrower’s income has not increased and spending has not fallen, refinancing merely moves the problem forward.
This creates a cycle: Financial pressure → Loan → Temporary relief → EMI burden → Financial pressure → New loan → Temporary relief. This is the invisible treadmill.
14. The phone has become both the wallet and the salesman
This is perhaps the most significant change. Earlier, financial persuasion occurred mainly through bank branches, agents, advertisements and personal relationships. Today the smartphone knows when the consumer is available, what products he uses and what financial offers can potentially be presented to him.
Digital technology can therefore become a remarkably efficient distribution mechanism. The same technology can also create behavioural nudges. RBI’s 2025 Digital Lending Directions specifically address the presentation of multiple loan offers and prohibit LSPs from using “dark patterns” in interfaces to nudge borrowers toward a particular loan that may not suit their requirements.
This is an important principle: technology should simplify financial decisions—not manipulate them.
15. The borrower may be financially stressed but digitally overconfident
Young consumers are comfortable with smartphones. They can order food in seconds, book flights instantly, buy shares from an app, transfer money through UPI—and obtain a loan digitally. This creates a dangerous psychological association: “If everything else is instant, credit should also be instant.”
But credit is different. A food order ends when the food is consumed. A loan can affect the next 12, 24, 36 or even 60 months of income. The speed of disbursement should therefore never determine the speed of decision-making.
16. The greatest generational danger: selling tomorrow’s income today
This is the central issue. A young person earning ₹40,000 today may think: “I can afford ₹8,000 EMI.” But what is actually being committed? Not merely ₹8,000 today. It is a portion of tomorrow’s salary + next month’s salary + next year’s salary.
When millions of young people begin consuming against future earnings, society gradually shifts from earning → saving → investing → building assets towards earning → borrowing → consuming → repaying → borrowing again. That is a profound economic and social transformation.
17. What happens to the next generation?
A generation raised in a permanent EMI environment may develop very different attitudes toward money. Savings may appear unnecessary. Credit may appear normal. Delayed gratification may disappear. Lifestyle may be judged by consumption rather than net worth.
A young employee may have a ₹8 lakh annual salary, ₹6 lakh outstanding personal loans, ₹2 lakh credit-card dues, a ₹3 lakh vehicle loan and almost no emergency savings. Yet the person may appear financially successful. This is the illusion of prosperity through borrowed money.
18. The invisible crisis is not necessarily a banking crisis
Banks and regulated lenders have risk-management systems. The deeper social concern is household resilience. What happens when a job is lost? Salary is reduced? Medical expenditure suddenly rises? A family member becomes unemployed? Interest rates rise? Several EMIs fall due simultaneously?
A household with no savings and high fixed debt obligations becomes extremely vulnerable. One income shock can trigger a chain reaction. One missed EMI can become a financial identity problem. Then comes collection pressure, credit-score damage, refinancing and family stress.
The consequences eventually move beyond finance. They enter marriage, mental peace, children’s education, family relationships and social stability.
19. The lender also has a responsibility
This article should not be interpreted as an argument against banks, NBFCs or FinTech companies. Responsible lending is socially valuable. Credit enables education, housing, entrepreneurship, medical treatment, consumption, asset creation and emergency support.
The problem arises when credit distribution becomes more sophisticated than financial education. A technologically advanced lending ecosystem must therefore build a technologically advanced borrower-protection ecosystem.
RBI’s framework already places significant emphasis on KFS, APR, disclosures, grievance redressal, consent for data use and responsible digital lending. The next step should be deeper behavioural protection.
20. What should change?
- The first question should not be “How much can we lend?” It should be: “How much can this customer safely repay?”
- The second should not be “Can we disburse instantly?” It should be: “Has the customer understood the commitment?”
- The third should not be “Can we sell a top-up?” It should be: “Does this customer actually need additional debt?”
- And the fourth should not be “Has the customer repaid correctly?” It should be: “Has the customer’s overall financial health improved?”
That would transform lending from a transaction into responsible financial service.
21. A new borrower-protection model
India could consider strengthening the digital lending ecosystem around five psychological safeguards:
- The 24-hour thinking principle. For non-emergency consumer loans, platforms could prominently encourage customers to review the loan before acceptance rather than creating artificial urgency.
- Total-cost display. Every loan screen should prominently show: Amount credited → Total repayment → Total interest → Total fees/charges → EMI → Tenure → APR; not hide these figures inside a lengthy agreement.
- Debt-load warning. If a borrower already has substantial outstanding obligations, the platform should display a clear warning: “Additional borrowing may materially increase your monthly financial burden.”
- Top-up suitability check. A customer who repeatedly takes top-ups should receive a financial-health warning rather than merely another sales offer.
- Financial-health score. The industry could eventually move beyond the traditional credit score. A borrower could be shown: Credit Score + Debt-to-Income + Savings Buffer + EMI Burden.
A good borrower should not merely be someone who pays EMIs on time. A good borrower should be someone whose financial health is improving.
22. What every borrower should do before pressing “Accept”
Before taking an instant loan, stop for ten minutes. Ask yourself:
- Do I really need this money?
- Can I solve the problem without borrowing?
- What is the APR?
- What is the total amount I will repay?
- What is the total EMI burden of all my loans together?
- What happens if my income stops for three months?
- Am I borrowing for an asset, an emergency or consumption?
- Am I taking this loan because I genuinely need it—or because the lender says I am eligible?
- Am I taking a new loan to repay an old loan?
- If the answer to the last question is yes, what has actually changed in my financial situation?
If nothing has changed, another loan may simply postpone the problem.
23. A simple rule for the new generation
Don’t ask: “How much loan can I get?” Ask: “How much debt can my life safely carry?”
Don’t ask: “How low is the EMI?” Ask: “How much will I pay in total?”
Don’t ask: “Will I get a top-up?” Ask: “Why would I need another loan after repaying this one?”
And don’t consider a good credit score a licence to borrow. A good credit score should give you bargaining power—not encourage you to consume more debt.
24. From instant credit to intelligent credit
India’s digital financial revolution is one of the country’s greatest achievements. UPI, mobile banking, digital KYC, automated underwriting and FinTech innovation can dramatically improve financial inclusion. But financial inclusion should not mean putting every person into the credit system. It should mean putting people into the financial system in a way that improves their long-term economic security.
The ultimate success of digital lending should therefore not be measured merely by the number of loans disbursed. It should also be measured by the number of borrowers who became financially stronger after borrowing. That is the difference between credit distribution and responsible credit creation.
The final question
The most dangerous loan is not necessarily the loan with the highest interest rate. It may be the loan that arrives at exactly the moment when a financially stressed person is psychologically unable to say “No.”
The future of India’s financial system will therefore depend on a difficult balance. FinTech companies must continue to innovate. Banks and NBFCs must continue to lend. Customers must continue to have access to credit. But technology must never become so good at selling debt that it becomes better at persuasion than the borrower is at judgment.
Because every instant loan has two sides. For the lender, it is an asset. For the borrower, it is a commitment of future income. And if an entire generation begins spending tomorrow’s income today, the consequences will not remain inside loan accounts. They will eventually appear in families, workplaces, consumption patterns, savings, mental peace and the economic resilience of the nation.
The real financial revolution, therefore, should not be: “Loan approved in 5 minutes.” It should be: “Financial decision understood in 5 minutes.” That is the kind of digital lending India should build.
Frequently Asked Questions
Why do instant loan offers feel so hard to refuse?
They arrive at moments of financial stress and use urgency, pre-approval and limited-period messages to reduce hesitation, so the mind asks how much it can get instead of whether it should borrow.
Is a pre-approved loan the same as free money?
No. Pre-approval means the lender is willing to lend, not that you can comfortably repay. Eligibility asks whether the lender can lend, while affordability asks whether you can repay without damaging your life.
Why should I look at APR and not just the interest rate?
APR is the annualised cost of credit including applicable charges such as processing and documentation fees. RBI requires regulated entities to disclose APR and a Key Fact Statement for digital loans.
Does a good repayment record mean I can safely take another loan?
Not necessarily. A good credit history shows repayment behaviour, but it does not mean more borrowing is advisable. Use a good score for bargaining power, not to take on more debt.
What should I do before accepting an instant loan?
Stop for ten minutes and ask whether you truly need the money, what the APR and total repayment are, what all your EMIs add up to, and whether you are borrowing to repay an older loan.
Are instant loan apps safe to use?
Only if the lender is a bank or an NBFC regulated by the RBI, and the app clearly shows the lender’s name, the full APR, all fees and a proper loan agreement. Be careful with apps that ask for access to your contacts or photos, or that pressure you to decide immediately.
What does a pre-approved loan offer actually mean?
It means the lender has pre-screened you for a loan up to a limit, based on your records. It is still a loan with interest, fees and repayment obligations, not a gift, and you are free to decline it.
Are instant loan apps safe?
They can be, if the loan comes from an RBI-regulated bank or NBFC. Under RBI’s digital lending rules the lender must give you a Key Fact Statement showing the APR and all charges before you accept, and the money should move directly between your bank account and the regulated lender’s account, not through a third-party wallet. If an app hides charges, asks for contact or photo access, or will not share the Key Fact Statement, walk away. This is general information, not investment, legal or medical advice.
What is the difference between loan eligibility and affordability?
The article says eligibility asks whether a lender can lend, while affordability asks whether you can repay without damaging your life. A person may be eligible for Rs 5 lakh and still be unable to repay it comfortably, so a lender’s willingness to lend is not proof that you should borrow.
Why should I not judge a loan only by its EMI?
The article says a small monthly figure sounds manageable because the mind understands monthly cash flow better than a multi-year commitment. It suggests asking what total amount you will repay. If a Rs 3 lakh loan eventually needs Rs 3.75 lakh or Rs 4 lakh to repay, that difference is the real cost of borrowing. The article notes that RBI’s Key Fact Statement framework is meant to make key loan information and the all-inclusive cost easier to understand before you commit.
Why do processing and other fees matter as much as the interest rate?
The article says borrowers may react strongly to a headline interest rate but pay less attention to a processing fee, documentation fee, verification charge or insurance, because they see several small numbers instead of one large cost. It says APR, the annualised cost of credit including applicable charges, is more meaningful than the headline rate alone, and that RBI’s digital lending framework requires regulated entities to disclose APR and provide a Key Fact Statement.
Related Reading
- India Needs Stronger Rules on Digital Lending to Protect Young Borrowers
- Debt Trap: When Financial Crisis Becomes a Psychological Emergency
- The Credit Card Trap: How a Small Piece of Plastic Is Quietly Rewiring Our Psychology
- Financial Wisdom Generation: 5 Bold Fixes for a Debt-Trap Culture
- Gold Loan Risks: 5 Questions to Ask Before Pledging Gold
See more of our stories on Google Search
Leave a Reply