

How to get out of debt trap in India starts with three moves: stop taking new loans to repay old ones, tell your lender early and ask in writing for rescheduling or restructuring, and get help for the stress itself, because fear is what usually pushes borrowers into the next bad decision.
A debt trap isn’t just a financial problem — it’s a psychological one: borrowers who take a new loan to repay an old one enter a cycle where fear and stress erode the very decision-making ability they need to escape it, and restructuring options like moratoriums, consolidation, and lower interest rates work because they restore hope first, which is what makes rational repayment possible again.
A debt trap is often viewed as a financial problem, but in reality it is also a psychological emergency. Behind every person struggling with overwhelming debt is a human being battling fear, shame, uncertainty, and hopelessness. As debts continue to grow, many borrowers stop thinking rationally and begin making desperate decisions that push them even deeper into financial distress.
In today’s digital economy, credit has become easier to obtain than ever before. Personal loans, instant lending apps, credit cards, Buy Now Pay Later (BNPL) schemes, and quick digital approvals have made borrowing almost effortless. While these financial innovations have improved access to credit, they have also increased the risk of chronic indebtedness for many individuals.
Key Takeaways
- A debt trap is as much a psychological emergency as a financial one—fear and stress erode the decision-making ability borrowers need to escape it.
- RBI’s December 2025 Financial Stability Report found that unsecured loans made up 53.1% of retail loan slippages at scheduled commercial banks.
- Restructuring options like moratoriums, loan rescheduling, and debt consolidation work because they restore hope first, which makes rational repayment possible again.
Table of Contents
What Does the Psychology of a Debt Trap Actually Look Like?
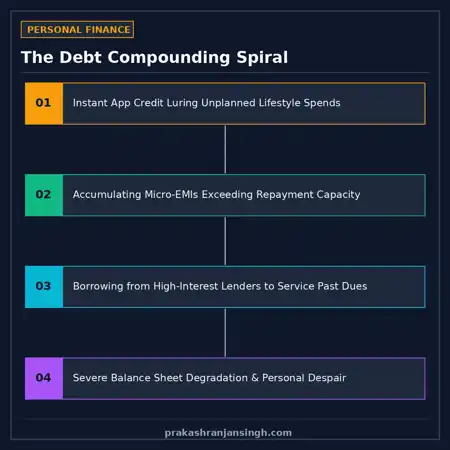
A person trapped in debt rarely wakes up one morning intending to default. The journey usually begins with a genuine financial need—a medical emergency, job loss, business failure, education expenses, or family obligations.
The real danger begins when one loan is repaid with another.
This creates a vicious cycle where the borrower is no longer earning enough to reduce the principal. Instead, most of the income goes toward paying interest and monthly installments. Every new loan provides only temporary relief while increasing long-term financial pressure.
As liabilities continue to rise, the borrower’s mental state changes dramatically, often bringing constant anxiety, sleepless nights, loss of concentration at work, fear of recovery calls, social isolation, and deep emotional exhaustion. At this stage, the problem is no longer merely financial. It has become a public health and social concern. RBI’s December 2025 Financial Stability Report found that unsecured loans accounted for 53.1% of retail loan slippages at scheduled commercial banks, even though overall bank asset quality remained stable.
Why Does Traditional Recovery Sometimes Backfire?
Many recovery systems focus primarily on collecting overdue payments. However, when a borrower reaches the stage of chronic debt distress, aggressive recovery efforts may worsen the psychological burden instead of improving repayment capacity.
A frightened borrower often loses the confidence to plan, work productively, or negotiate solutions. Stress reduces decision-making ability, creating a cycle in which fear leads to poorer financial choices, making repayment even more difficult.
How Can Financial Relief Actually Restore Hope?
One of the most effective ways to stabilize a distressed borrower is to reduce immediate financial pressure. This can be achieved through responsible financial restructuring mechanisms such as temporary moratoriums during genuine hardship, loan rescheduling with affordable installments, extension of repayment tenure, debt consolidation into a single manageable loan, lower interest rates in deserving cases, structured settlement plans, and financial counselling and budgeting assistance.
These measures do not erase responsibility. Instead, they give borrowers breathing space to recover emotionally, regain employment or income stability, and restart disciplined repayment. When panic decreases, rational thinking returns.
Does Mental Recovery Really Come Before Financial Recovery?
The greatest benefit of restructuring is often psychological rather than financial.
The moment a borrower knows that repayment has become manageable, fear begins to fade. Confidence slowly returns. The person can sleep better, focus on work, rebuild family relationships, and start planning for the future.
A calmer mind is more capable of earning, saving, and repaying debt responsibly.
Whose Responsibility Is It to Prevent Debt Traps?
Preventing debt traps requires cooperation from everyone. Financial institutions should strengthen responsible lending and support viable restructuring for borrowers facing genuine hardship. Governments can promote financial literacy, regulate predatory lending practices, and encourage fair debt resolution frameworks. Employers can provide financial wellness programs and counselling for employees experiencing financial stress. Families should encourage open conversations about money instead of allowing debt to become a source of shame. Borrowers must avoid taking new loans solely to repay old ones without a realistic repayment strategy and should seek help early before debt becomes unmanageable.
Every successful debt restructuring is more than an accounting exercise. It can restore dignity, preserve families, and protect well-being.
The objective should not simply be recovering money. It should be helping individuals recover their ability to live productive and meaningful lives.
A compassionate financial system does not weaken credit discipline—it strengthens it by giving honest borrowers a fair opportunity to rebuild.
Because when hope is restored, repayment becomes possible. When panic is reduced, productivity returns. And when society chooses rehabilitation alongside responsibility, everyone benefits.
How to Get Out of Debt Trap in India: 6 Practical Steps
The steps below follow the logic of this article: reduce the pressure first, then rebuild repayment. They are general information, not personal financial, legal or medical advice.
- Stop borrowing to repay. Do not take a new loan, app loan or card cash advance to pay an old EMI. It lowers this month’s pressure and raises every later month’s.
- Write down every debt. List the lender, amount outstanding, interest rate, EMI and due date. Once minimum payments are safe, clear the costliest debt first.
- Talk to the lender before you miss a payment. Ask in writing for rescheduling, a longer tenure or restructuring, the same options described above, and keep a copy of every request and reply.
- Know the limits on recovery. RBI has told banks, NBFCs and other regulated lenders not to harass borrowers or call them at odd hours, and in 2022 it extended limits on recovery-call hours to all of them (RBI press release). If a lender does not resolve your complaint within 30 days, or you are unhappy with its reply, you can take it to the RBI Ombudsman free of cost through the RBI complaint portal.
- Treat the stress as part of the problem. If anxiety or sleeplessness is affecting your decisions, the government’s Tele-MANAS helpline offers toll-free counselling on 14416 or 1800-89-14416.
- Rebuild slowly. Once EMIs are manageable, build a small emergency buffer and keep one monthly budget, so the next shock does not send you back to a new loan.
The scale is national. RBI’s December 2025 Financial Stability Report put household debt at 41.3% of GDP at the end of March 2025, against a five-year average of 38.3%, while noting that India’s household debt remains lower than most peer emerging economies. Anyone searching for how to get out of debt trap in India is therefore not alone, and the sooner the conversation with the lender starts, the more options remain.
Frequently Asked Questions
How to get out of debt trap in India?
Stop taking new loans to repay old ones, list every debt with its interest rate and EMI, and approach your lender early, in writing, for rescheduling or restructuring. Clear the costliest debt first once minimum payments are safe, and get help for the stress, because fear drives poor financial decisions. This is general information, not personal financial advice.
Why is a debt trap considered a psychological emergency, not just a financial one?
As liabilities rise, borrowers often experience constant anxiety, sleepless nights, loss of concentration, fear of recovery calls, and social isolation. This stress reduces decision-making ability, creating a cycle in which fear leads to poorer financial choices, which is why the problem is treated as a public health and social concern, not just an accounting one.
Why can aggressive debt recovery backfire?
When a borrower reaches chronic debt distress, aggressive recovery efforts can worsen the psychological burden rather than improving repayment capacity. A frightened borrower often loses the confidence to plan, work productively, or negotiate solutions, making repayment even harder.
What kinds of financial relief actually help borrowers recover?
Responsible restructuring options include temporary moratoriums during genuine hardship, loan rescheduling with affordable installments, extended repayment tenure, debt consolidation into one manageable loan, lower interest rates in deserving cases, and financial counselling. These measures don’t erase responsibility, but they give borrowers breathing space so panic decreases and rational repayment becomes possible again.
Where can a borrower in debt distress get help in India?
For stress and anxiety, the government’s Tele-MANAS helpline offers toll-free counselling on 14416 or 1800-89-14416. For a dispute with a bank or NBFC, complain to the lender first, then escalate to the RBI Ombudsman through the cms.rbi.org.in portal if there is no reply within 30 days or the reply is unsatisfactory. The service is free.

Leave a Reply