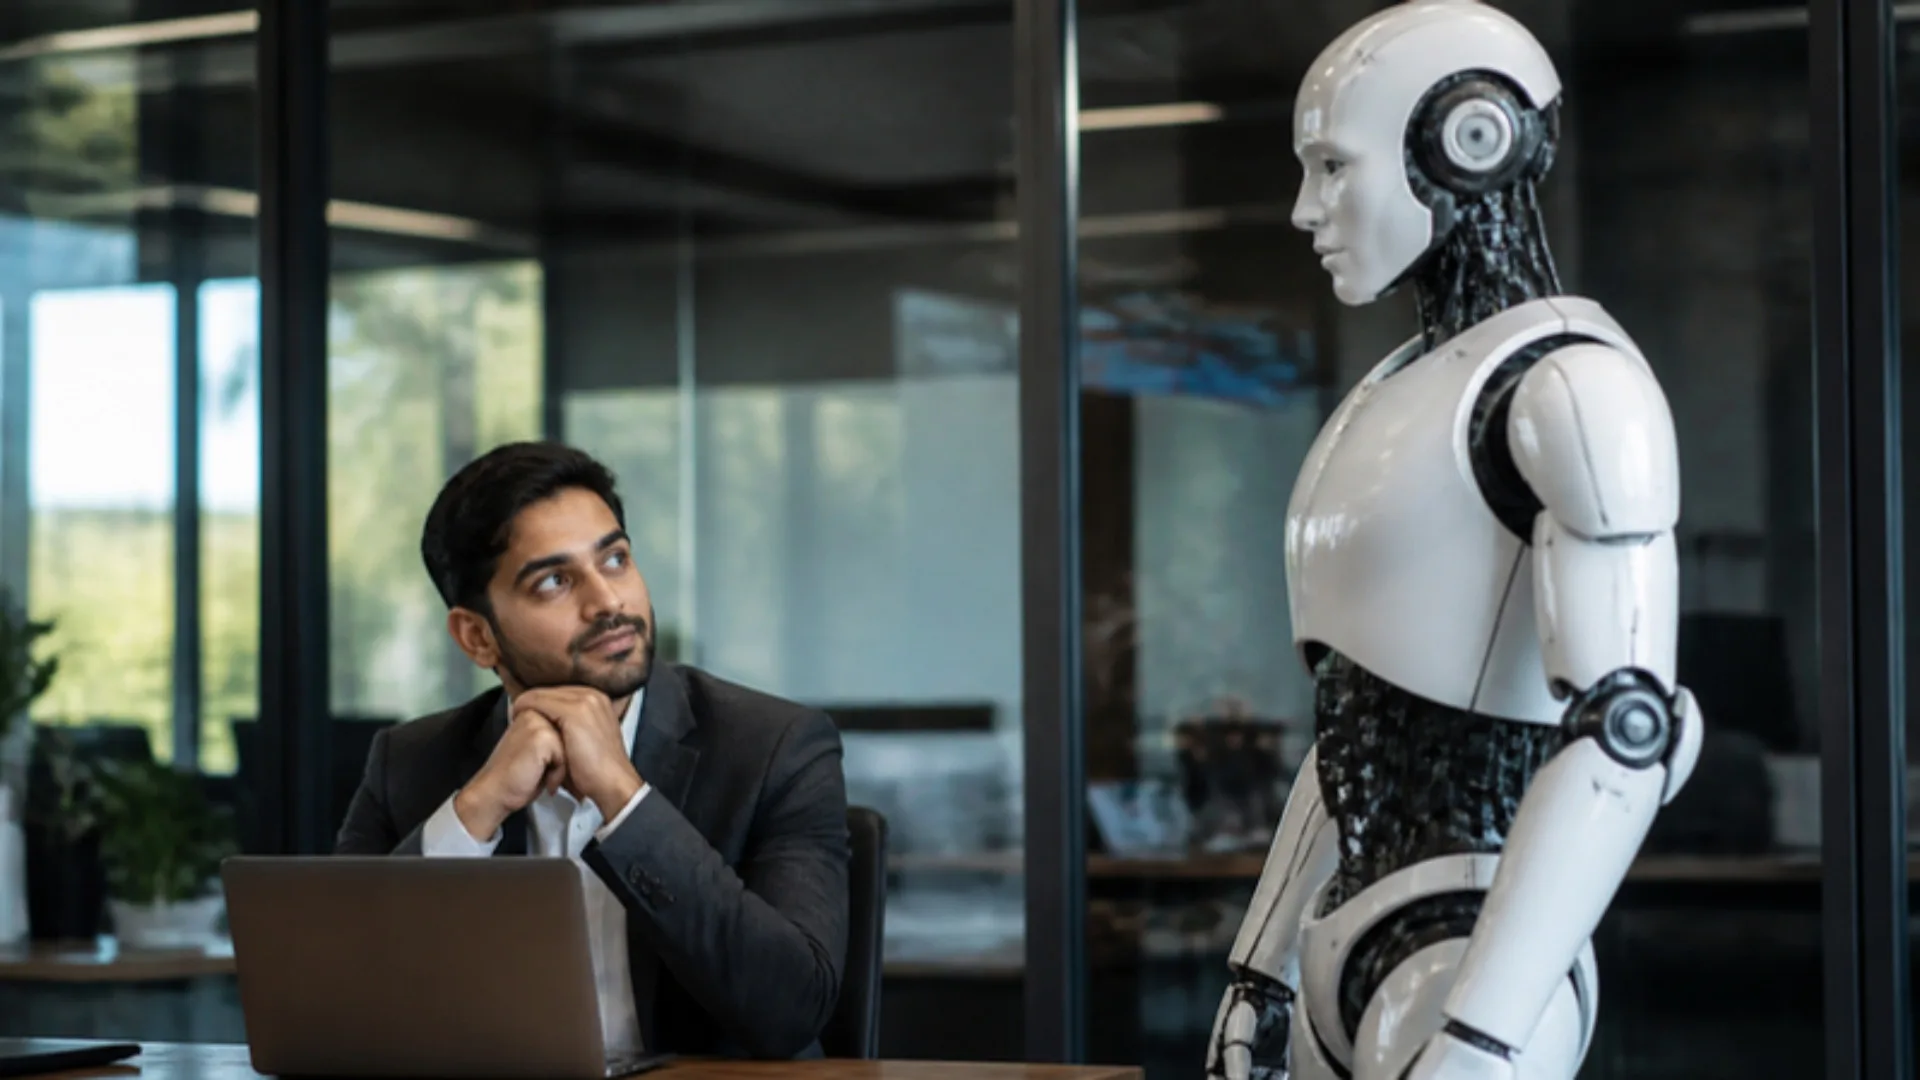
When billionaires predict a world without scarcity, should ordinary young people gamble away their financial security today?
Imagine a young professional who has just started earning. He has responsibilities, dreams of owning a house, supporting his parents, educating his children and living a financially independent life after retirement. He has been taught by his family to save a portion of his income, control unnecessary expenses, invest regularly and prepare for uncertain circumstances.
Suddenly, one of the world’s most influential technology entrepreneurs tells him that saving money for the distant future is pointless because Artificial Intelligence (AI) and robots will soon produce so much that money itself may become irrelevant. What should this young person believe? The financial discipline taught by generations of families, or the extraordinary promise of a future that has not yet arrived?
The Elon Musk saving for retirement debate was reignited on 29 October 2026, when he wrote on X, as reported by Business Insider and Mint, that saving money for the distant future is pointless in an era of super-intelligent abundance. His argument rests on the possibility that AI, robotics and advanced energy technologies will create extraordinary productivity, make goods and services abundantly available, reduce prices and eventually make conventional employment and money less important.
Earlier, in January 2026, he had also suggested that within 10 to 20 years people might not need to save for retirement because technological abundance could fundamentally change the economics of human life. It is an exciting vision. It is also a proposition that deserves serious examination before an entire generation starts treating financial responsibility as an outdated habit.
Key Takeaways
- Producing wealth is not sharing wealth — abundance, if it comes, depends on who owns the robots, factories and platforms, not only on how much they produce.
- A billionaire’s prediction is not your financial plan — someone who owns productive assets can absorb being wrong; a salaried employee with a home loan cannot.
- Embrace AI, keep saving — an emergency fund, insurance, regulated long-term investments and better skills protect you whichever future arrives.
Table of Contents
- 1. Elon Musk Saving for Retirement: A Beautiful Future Is Not a Guaranteed Future
- 2. The Biggest Economic Question: Who Will Pay the People Who Lose Their Jobs?
- 3. Zero Inflation and Zero Prices Are Two Very Different Things
- 4. The Psychological Damage of Abandoning Financial Discipline
- 5. The Contradiction of Wealthy Technology Owners Advising Ordinary People Not to Save
- 6. The Unanswered Question of Who Will Control Humanity’s Future
- 7. Saving Is Not an Outdated Economic Theory
- 8. India’s Young Generation Cannot Afford to Ignore Financial Realities
- 9. A New Financial Philosophy: Embrace AI, but Do Not Abandon Saving
- 10. The Future of Humanity Must Be About Dignity, Purpose and Independence
- Conclusion: Never Sacrifice a Certain Financial Habit for an Uncertain Technological Promise
- Frequently Asked Questions
1. Elon Musk Saving for Retirement: A Beautiful Future Is Not a Guaranteed Future
There is little doubt that AI and robotics have the potential to transform human civilisation. Machines can increase manufacturing capacity, improve agricultural productivity, assist medical professionals, accelerate scientific discoveries and make education more accessible. Services that are expensive today may become considerably cheaper tomorrow.
But there is a fundamental difference between producing more wealth and ensuring that everybody receives a fair share of that wealth. Who will own the robots? Who will own the factories, technology platforms, patents, computing infrastructure, energy resources and distribution networks? If a handful of corporations own most of the productive technology, increased productivity may generate extraordinary profits for those owners without automatically making every citizen wealthy. That is the same question raised in our look at wealth moving from ordinary investors to billionaires.
Economic prosperity is not simply about how much a society produces. It is also about who owns the productive assets, who earns income, who controls distribution and who can afford access to the resulting products and services. A world producing enormous wealth can still have financially insecure citizens if the benefits are not distributed fairly. The promise of abundance therefore requires more than technological advancement. It requires an economic and institutional framework that makes abundance accessible to ordinary people.
2. The Biggest Economic Question: Who Will Pay the People Who Lose Their Jobs?
Consider a simple example. A company employs 10,000 people to manufacture products. With advanced robotics and AI, it can produce the same quantity with only 1,000 employees. The company may reduce production costs, increase profitability and offer products at lower prices. But what happens to the remaining 9,000 employees?
They lose their regular salaries, purchasing power and financial independence. If millions of companies follow similar models, the question becomes much larger than individual unemployment. Who will purchase the products manufactured by automated factories if a significant section of the population no longer has adequate income? Production creates supply, but purchasing power creates demand. An economy cannot survive merely by producing unlimited goods; it also needs a mechanism through which people can access those goods. The job-market side of this story is already visible in AI layoffs reshaping careers.
Mr. Musk has discussed universal high income, including government payments, as a possible response to AI-driven unemployment. However, this introduces another major question: how will governments finance such payments, how will they distribute them, and how will they ensure that citizens receive a fair share of technological productivity? These are serious economic and public-policy questions, not minor details that can be ignored while advising people to stop saving.
3. Zero Inflation and Zero Prices Are Two Very Different Things
The assumption that technological productivity will bring inflation down to zero also requires careful examination. AI may reduce the cost of software, certain professional services, manufacturing and information processing, and robotics may make several products cheaper through automation. However, not every resource can be produced without limitations.
Land in a desirable city, housing near employment centres, agricultural land, water, electricity infrastructure, natural resources and certain medical facilities will continue to face physical and geographical constraints. Even if robots manufacture millions of houses, prime land in Delhi, Mumbai, Bengaluru or other desirable locations will remain limited. Similarly, medical technology may improve dramatically, but access to specialised facilities, infrastructure and scarce resources will still involve economic choices. Prices of some products may fall substantially while prices of other essential resources continue to rise.
There is also an important distinction between deflation in selected goods and a sustained fall in the general price level. If prices fall while incomes and employment also decline, the outcome may not be prosperity. A cheaper product is beneficial, but a person without purchasing power may still be unable to afford it.
4. The Psychological Damage of Abandoning Financial Discipline
The greatest danger of such advice may not be economic. It may be psychological. Young people already live in an environment of instant gratification. Credit cards, instant personal loans, buy-now-pay-later facilities, online shopping, social-media lifestyles and easy digital payments have made spending extremely convenient, and many young earners already spend against expected future income rather than their actual capacity. Now imagine adding another justification: why save today when AI will provide everything tomorrow? Such thinking can gradually weaken several important habits.
- The habit of delayed gratification: financial discipline teaches people to postpone unnecessary consumption to achieve larger life goals. If tomorrow is assumed to be automatically prosperous, the motivation to sacrifice today may disappear.
- The sense of personal responsibility: young people may begin to believe that future technology or government assistance will take care of their needs, weakening the motivation to prepare for uncertainty.
- The confidence to face difficulties: savings provide psychological security. A person with an emergency fund can face unemployment, illness or a business setback with greater confidence than someone living entirely on monthly income.
- The motivation to improve earning capacity: the desire to build a better financial future encourages people to learn, work harder, acquire skills and explore opportunities. Removing the importance of personal preparation may weaken this in some individuals.
- The ability to make independent decisions: financial independence gives people the freedom to leave exploitative employment, reject unsuitable financial commitments and support their families without constantly depending on others.
The objective should not be to make young people afraid of spending or obsessed with accumulating money. It should be to make them financially confident, responsible and independent. A generation that loses the habit of preparing for tomorrow may discover the consequences when tomorrow arrives differently from what it expected.
5. The Contradiction of Wealthy Technology Owners Advising Ordinary People Not to Save
There is an important difference between the financial position of a technology billionaire and that of an ordinary salaried employee. A billionaire may own companies, intellectual property, equity, businesses, real estate and other productive assets. Even when the value of money changes, ownership of productive assets may continue to generate economic power. An ordinary young professional, on the other hand, may depend entirely on a monthly salary. The billionaire has multiple sources of wealth creation; the employee may have only one source of income.
The billionaire can absorb substantial financial uncertainty. A young employee who loses a job while carrying a home loan, personal loan and credit-card debt may face a completely different reality. This difference in financial exposure must not be ignored. There is nothing wrong with technology leaders sharing their vision of the future, and their innovation deserves recognition. But a prediction made from a position of extraordinary wealth should not automatically become personal financial advice for people who have limited savings and significant responsibilities. The financial consequences of being wrong are not equally distributed.
6. The Unanswered Question of Who Will Control Humanity’s Future
AI is not simply another consumer product. It is becoming an important part of the economic infrastructure of civilisation. A relatively small number of technology companies and institutions control significant parts of advanced computing, AI models, data infrastructure and related investment. This concentration deserves public attention, as the market excitement around the Anthropic IPO also shows.
If essential services, employment opportunities, financial infrastructure, education and information systems become increasingly dependent on a few technology platforms, society must ask questions about ownership, competition, accountability, privacy and access. Could excessive dependence on a limited number of technology owners create new forms of economic power over ordinary citizens? It is a legitimate question.
However, there is no established evidence that a secret agenda to control humanity is behind any particular prediction about future abundance. Criticism should be based on verifiable economic structures and actual concentrations of power rather than unproven allegations. The more useful concern is whether democratic institutions, regulators and citizens will have sufficient influence over technologies that could shape the future of work and economic opportunity. Humanity must remain the beneficiary of technology, not merely a dependent consumer of services controlled by others.
7. Saving Is Not an Outdated Economic Theory
For generations, families have followed a simple financial philosophy: earn honestly, spend carefully, save regularly, invest wisely, avoid unnecessary debt, prepare for emergencies and build assets over time. This philosophy has survived changes in currencies, governments, banking systems, industrial revolutions and technology. It is not based on opposition to innovation. It is based on the recognition that human life contains uncertainty.
People lose jobs. Businesses fail. Medical emergencies arise. Family responsibilities increase. Markets experience downturns. Retirement eventually arrives. Savings create a financial buffer against these realities. A person who saves and invests regularly also benefits from the power of compounding: even modest contributions made consistently over a long period can build meaningful wealth. Financial discipline is not merely about accumulating currency; it is about developing the ability to manage limited resources, control impulses and make decisions in the interest of long-term security. Technology may change how people earn, spend and invest. It does not automatically eliminate the need for financial discipline.
8. India’s Young Generation Cannot Afford to Ignore Financial Realities
The Indian economic environment makes this discussion particularly important. Millions of young Indians are entering employment with aspirations of independent living, better housing, personal vehicles, foreign travel and improved lifestyles. At the same time, many are exposed to unstable employment, competitive job markets, rising urban living costs and easy digital borrowing. A young employee in Bengaluru, Delhi, Mumbai or Hyderabad may be earning a reasonable salary but also managing rent, transportation, education loans, family responsibilities and lifestyle expenses.
What happens if that employee loses a job during an economic slowdown or an AI-driven restructuring, as discussed in our article on big-tech voluntary exit offers? Will future abundance pay the next month’s rent, clear the outstanding personal loan or meet an immediate medical expense? Until a reliable and functioning system of universal economic security actually exists, individuals must prepare for their own financial responsibilities.
India also has a large population working in agriculture, manufacturing, retail, transportation, banking, administration and informal services. The speed and impact of AI adoption will differ considerably across these sectors, and the benefits of advanced technology will not reach every worker at the same time or in the same manner. For Indian youth, financial literacy, professional skills and adaptability must develop together. The mindset side of this is covered in the salaried investor’s dilemma.
9. A New Financial Philosophy: Embrace AI, but Do Not Abandon Saving
Young people should not reject AI because they fear unemployment. Equally, they should not abandon financial planning because they expect AI to make them wealthy. A balanced approach is more sensible:
- Save before spending. Allocate a fixed portion of income towards savings and investments immediately after receiving a salary.
- Build an emergency fund. Aim initially for three to six months of essential expenses, increasing the buffer where employment is uncertain or family responsibilities are high.
- Avoid unnecessary debt. Do not finance an expensive lifestyle through personal loans, revolving credit-card balances or high-interest digital lending.
- Protect against financial shocks. Understand the importance of suitable health insurance and, where family members depend on your income, adequate term life insurance.
- Invest for long-term goals. Use suitable diversified investments according to your risk capacity and time horizon. Consider provident fund, NPS, diversified mutual funds, deposits and other regulated financial products as appropriate.
- Invest in your own capabilities. Learn AI tools, improve communication, develop analytical skills and acquire knowledge that makes you more adaptable in a changing employment market.
- Build assets, not just consumption. Gradually develop financial assets and productive capabilities rather than measuring success only through expensive possessions.
Finally, never make a financial decision solely on the basis of somebody else’s prediction. Even the most influential technology entrepreneur cannot guarantee the economic conditions of the next 10, 20 or 30 years.
10. The Future of Humanity Must Be About Dignity, Purpose and Independence
There is a deeper question that goes beyond money. If AI performs most human tasks, robots manufacture most products and machines provide most services, what will give human life meaning? Work is not merely a source of income. It provides structure, discipline, identity, social interaction, responsibility and a sense of contribution. For many people, professional achievement is also connected with self-respect and family dignity.
A future in which people have access to abundant goods but lack purpose, meaningful participation and control over their lives may not necessarily be a successful civilisation. Young people need opportunities to create, discover, build relationships, contribute to society and develop their physical and intellectual capabilities. Technology should reduce unnecessary hardship and free human beings to pursue meaningful activities. It should not encourage passivity, dependency or the abandonment of personal responsibility. The real measure of technological progress should be whether ordinary people become healthier, more educated, financially secure, independent and socially empowered.
Conclusion: Never Sacrifice a Certain Financial Habit for an Uncertain Technological Promise
Elon Musk may ultimately be right about the extraordinary productive capacity of AI and robotics. Humanity may enter an era in which many goods and services become dramatically cheaper and the traditional relationship between employment, income and consumption changes. But there is a long distance between technological possibility and economic reality. The technology must work, productivity gains must spread, ownership must not become excessively concentrated, institutions must adapt and ordinary people must receive a fair share of the benefits. Until these conditions become a functioning reality, asking young people to abandon savings is an unnecessary gamble with their future.
The traditional philosophy of financial discipline does not prevent anyone from enjoying technological progress. On the contrary, savings provide the freedom to adapt, learn, invest, take calculated risks and survive difficult transitions. Young people should be ambitious enough to embrace AI, intelligent enough to understand its limitations and disciplined enough to protect their financial future.
Remember, whatever the Elon Musk saving for retirement debate decides: you may live to witness a world where robots do most of the work, but until that world actually arrives, your financial responsibilities will still be waiting for you. Do not exchange your financial independence today for somebody else’s promise of abundance tomorrow.
This article is general information and opinion, not personal investment advice. Statements attributed to public figures reflect press reports; please verify current positions from original sources.
Frequently Asked Questions
What did Elon Musk say about saving for retirement?
According to press reports, in late October 2026 Mr. Musk said saving for the distant future is pointless in an era of super-intelligent abundance. In January 2026 he had said retirement saving might become irrelevant within roughly 10 to 20 years. These are predictions, not guarantees or financial advice.
Why does Elon Musk say not to save?
His argument is that AI, robotics and cheap energy could make goods and services so abundant that money and conventional employment matter less. He has also discussed a universal high income as a possible response to job losses.
Should I stop saving because of AI?
No. Savings protect you against job loss, illness and uncertainty whichever future arrives. A prediction of future abundance cannot pay today’s rent, EMIs or medical bills.
What is universal high income?
It is an idea that governments or institutions could pay citizens a regular income if AI takes over many jobs. No such system exists today, and questions of funding and fairness remain unanswered.
Will AI make everything cheap?
AI may lower the cost of software, information work and some manufactured goods. Scarce resources such as prime urban land, water and specialised medical facilities may stay expensive.
How much emergency fund should a young Indian keep?
A common starting guide is three to six months of essential expenses, and more if income is uncertain or you support dependants. Keep it in accessible, low-risk options.
How can I prepare for AI changing my job?
Build savings, avoid high-cost debt, keep insurance in place and keep learning useful skills, including how to use AI tools in your field.
Related Reading
- AI Layoffs Are Reshaping Careers
- Microsoft, Google, Amazon, Meta and the AI Revolution
- The Wealth Transferring from Ordinary Investors to Billionaires
- The Salary Investor’s Dilemma
- The AI Gold Rush and the Anthropic IPO
See more of our stories on Google Search
Leave a Reply