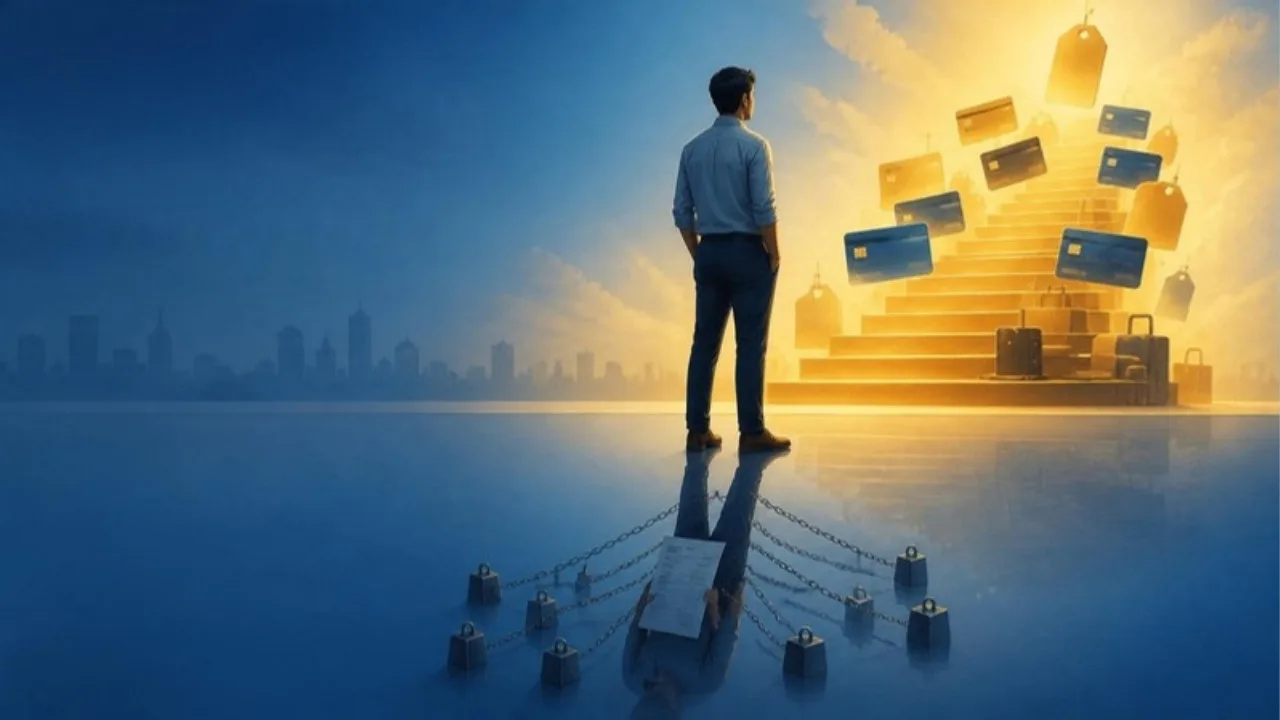
The illusion of affordability is the belief that you can afford something simply because a lender is willing to finance it. A credit limit is not income, and every lender sees only its own EMI, while you must pay all of them from the same salary.
The biggest trap of modern life is not poverty. It is the illusion of affordability.
Key Takeaways
- Offers are not income. A credit limit or a pre-approved loan shows what a lender will lend, not what you can comfortably repay.
- Small EMIs add up. Each lender sees only its own EMI, but you pay every EMI from the same salary, so ten small instalments are a heavy burden.
- Test before you borrow. Ask whether you could still pay all your EMIs comfortably if your income did not rise for the next 3 years.
Table of Contents
- Why Is the Illusion of Affordability the Biggest Trap of Modern Life?
- How Does Credit Card Psychology Make Debt More Dangerous?
- What Is the Financial Treadmill of Modern Life?
- Is the Real Problem Loans, or Excessive and Unthoughtful Credit?
- What One Question Should You Ask Before Your Next Loan?
- What Should You Remember About Credit and Real Wealth?
- Frequently Asked Questions
Why Is the Illusion of Affordability the Biggest Trap of Modern Life?
You earn ₹50,000 a month.
The bank says: “Congratulations! You are eligible for a ₹10 lakh personal loan.”
The credit-card company says: “Your limit has been increased to ₹3 lakh.”
The app says: “Buy now. Pay later.”
The showroom says: “Just ₹9,999 EMI per month.”
The online shopping site says: “No-cost EMI available.”
And slowly, without realising it, you begin to believe: “I can afford all this.”
But here is the brutal truth. A credit limit is not your income. A loan offer is not your wealth. An EMI is not a small expense when you have ten of them.
This is how the modern financial trap begins. One loan looks manageable. One credit-card bill looks manageable. One EMI looks manageable. One more loan for an emergency also looks manageable.
But remember: every lender sees only their EMI. You have to pay all the EMIs from the same salary.
And this is where human psychology becomes the biggest victim. When we borrow, our mind says:
- “I will get a promotion.”
- “My salary will increase.”
- “I will manage somehow.”
- “It is only ₹5,000 EMI.”
- “Everyone is buying. Why should I wait?”
The financial industry understands this psychology extremely well. So they don’t sell you a ₹1.5 lakh mobile phone. They sell you: “Just ₹4,999 per month!”
They don’t show you the burden of the total cost. They make you fall in love with the small monthly number. And the brain gets trapped.
How Does Credit Card Psychology Make Debt More Dangerous?
Cash hurts. When ₹10,000 physically leaves your pocket, you feel the pain. But swipe a credit card for ₹10,000? It doesn’t feel the same.
Why? Because the pleasure of buying happens today, while the pain of paying is postponed. That is the magic, and danger, of credit. You enjoy today. The bill comes later.
Then comes the minimum due. You pay a small amount and feel relieved. But the outstanding balance remains, and charges may continue according to the card terms.
Then you take a personal loan to clear the card. Then you use the card again. Then another EMI begins. And slowly, a dangerous chain is created:
Credit card → Personal loan → EMI → Another card → More debt
What Is the Financial Treadmill of Modern Life?
Then comes the most tragic part. You start working harder. You want a salary hike. You take more responsibility. You do overtime. You sacrifice family time. You postpone your dreams. You run faster every year.
But where does the additional income go?
- EMI.
- Interest.
- Fees.
- Outstanding balances.
- Another EMI.
And suddenly you realise something shocking: you have been working harder every year, but you are not becoming financially free. You are simply maintaining a financial structure created by your past borrowing.
This is the financial treadmill of modern life:
Earn more → Spend more → Borrow more → Pay more EMI → Need to earn even more
You keep running. But your financial position may not move forward.
Is the Real Problem Loans, or Excessive and Unthoughtful Credit?
The real problem is not loans. It is excessive and unthoughtful credit.
A home loan may help build an asset. An education loan may create future earning capacity. A business loan may generate income.
Credit, when used wisely, can transform lives. But borrowing to maintain a lifestyle you cannot afford can quietly destroy your future.
The most dangerous purchase is often not something you need. It is something you buy because “everyone else has it.”
Social media has made this worse. We see the new phone, the new car, the foreign vacation, the luxury watch, the five-star hotel. But we don’t see the EMI, the credit-card bill, the personal loan, the financial stress, the sleepless nights.
Social media shows the lifestyle. It hides the liability.
What One Question Should You Ask Before Your Next Loan?
“If my income does not increase for the next 3 years, can I still comfortably pay all my EMIs?”
Not just this EMI. All EMIs.
Because financial institutions may offer you credit. But nobody can give you your financial freedom back once too much of your future income has already been committed.
What Should You Remember About Credit and Real Wealth?
- Your credit limit is not your net worth.
- Your ability to pay the minimum due is not financial health.
- A pre-approved loan is not a reward. It is an offer to borrow.
- The person who owns less debt may be richer than the person who earns more.
And perhaps the greatest financial achievement in modern life is not having access to unlimited credit. It is having the courage to say: “No, I don’t need to borrow for this.”
Because real wealth is not about how much you can buy today. Real wealth is how much of your future income and peace of mind you still own.
Share this with someone who is earning well but still wondering: “Why am I working so hard, yet never feeling financially free?”
Frequently Asked Questions
What is the illusion of affordability?
It is the belief that you can afford something because a lender approves a loan, raises your card limit or offers a small EMI. Approval shows what a lender will lend, not what your salary can comfortably repay.
Is a credit limit the same as income?
No. A credit limit is borrowed money that must be repaid, with charges as per the card terms. It does not increase your income or your net worth.
Why do many small EMIs become a problem?
Every lender sees only its own EMI, but you must pay all of them from the same salary. One EMI may look manageable, while ten of them can take away most of your income.
Are all loans bad?
No. A home loan may help build an asset, an education loan may raise future earning capacity and a business loan may generate income. The real problem is excessive and unthoughtful credit used to maintain a lifestyle you cannot afford.
What should I ask myself before taking a new loan?
Ask whether you could still comfortably pay all your EMIs, not just the new one, if your income did not increase for the next 3 years.
Related Reading
- The Credit Card Trap: How a Small Piece of Plastic Is Quietly Rewiring Our Psychology
- Debt Trap: When Financial Crisis Becomes a Psychological Emergency
- The Hidden Cost of Living: How Psychological Management Can Change It
- Gold Loan: When the Family’s Last Resort Becomes a Debt Trap
- The Psychology of Easy Money: How Fintech Is Changing India’s Borrowing Pattern
Leave a Reply