An Indian wealth philosophy starts from one simple point: a financial strategy that built wealth in America will not automatically build security for an Indian family. Money is universal, but taxes, healthcare, pensions, family duties and the psychology of wealth are not. Global lessons are valuable, but they must be translated into Indian circumstances.
This article is general information, not investment, legal or medical advice.
From Warren Buffett to Robert Kiyosaki, the world has plenty of investment wisdom. But can a philosophy born in a different economic and cultural environment fully explain what wealth means to an Indian family?
There is a powerful assumption hidden inside much of today’s global personal-finance industry: if a financial strategy created wealth in America, it should create wealth everywhere. It sounds logical. But it is not necessarily true.
Money may be universal. Human needs are not. An American household, an Indian middle-class family, a Japanese retiree and an African entrepreneur may all invest in the same global financial market, yet their definition of financial security can be completely different.
Their income is different. Their taxation is different. Their healthcare systems are different. Their pensions are different. Their family responsibilities are different. Their relationship with property, gold, debt and inheritance is different. And perhaps most importantly, their psychology of wealth is different.
This is where India needs to develop its own financial vocabulary. Not by rejecting Warren Buffett, Robert Kiyosaki or other global financial thinkers, but by understanding what their lessons mean when translated into Indian circumstances.
Key Takeaways
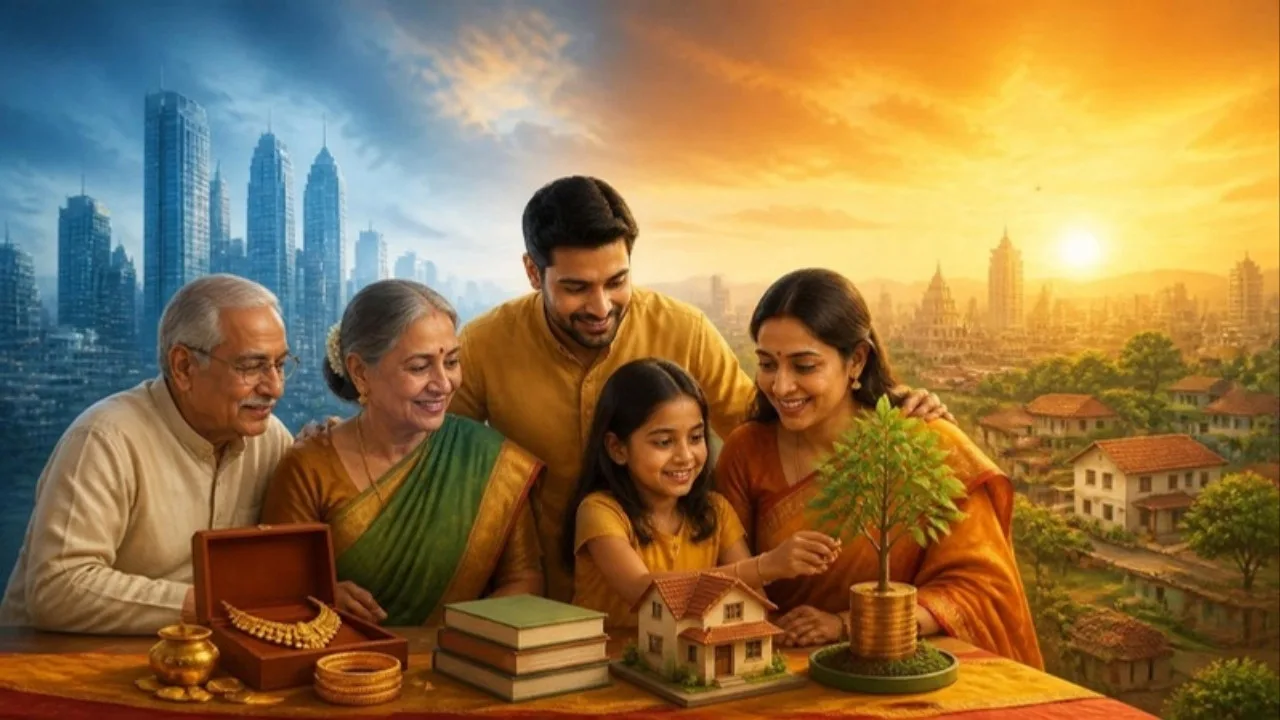
- Wealth is more than net worth. For Indian families it includes a home, children’s education, support for parents, gold, relationships, health cover and peace of mind.
- Adapt, do not copy. Buffett’s patience and Kiyosaki’s financial education are universal ideas, but their specific strategies must be fitted to Indian taxes, inflation, family duties and products.
- Keep the wisdom, remove the weaknesses. A hybrid model combines Western financial discipline with Indian family thinking, social capital and the idea of enough.
Table of Contents
- Why does Indian wealth philosophy go beyond money alone?
- The Indian family is itself an economic institution
- But Indian society is changing rapidly
- What Buffett actually teaches, and what India can adapt
- Kiyosaki’s message is more useful as a framework than as a prescription
- Is the family home an asset or a liability?
- India’s hidden wealth: social capital
- Gold tells an important Indian story
- Wealth creation in India must include the next generation
- But tradition has a danger too
- India’s greatest financial asset may be its human capital
- The Indian definition of financial freedom should be broader
- The psychology of enough
- India does not need less financial ambition
- The real lesson from Buffett and Kiyosaki
- India’s future wealth model may be a hybrid
- The new Indian wealth mantra
- Conclusion: Wealth is not a number on a spreadsheet
Why does Indian wealth philosophy go beyond money alone?
For centuries, Indian society has viewed prosperity through a much wider lens than the size of a bank account. The traditional Indian idea of Artha is certainly connected with material prosperity and economic security, but it has historically existed alongside Dharma, Kama and Moksha. That is fundamentally different from defining success exclusively through net worth.
For many Indian families, wealth means:
- owning a home,
- educating children,
- supporting parents,
- helping siblings,
- maintaining family dignity,
- possessing some gold,
- having social relationships,
- having a stable career,
- being able to face medical emergencies,
- supporting children’s marriages,
- leaving something for the next generation,
- contributing to society,
- and finally, having peace of mind.
A person with ₹5 crore may still feel financially insecure. Another person with a modest house, no major debt, children settled, adequate retirement savings and strong family relationships may consider himself wealthy.
Both definitions are real. This is why the Western financial industry’s obsession with numerical net worth cannot completely describe Indian prosperity.
The Indian family is itself an economic institution
One of the biggest differences between Western and Indian financial planning is the role of the family. An individual’s financial decision frequently affects several generations.
A young Indian professional may be saving not only for retirement but also for: parents + marriage + children + education + housing + emergencies + family obligations. The financial planner who sees only an individual’s balance sheet may therefore miss half the story.
In India, financial decisions are often intergenerational. Parents support children. Children support parents. Siblings help each other. Family-owned property remains within generations. Gold may move from grandmother to daughter to granddaughter. A house may become an inheritance rather than merely an investment.
This creates a very different definition of financial freedom. For many Indians:
Financial freedom means having enough resources to fulfil responsibilities without becoming a burden on the next generation.
That is a broader concept than simply generating passive income.
But Indian society is changing rapidly
It would also be wrong to romanticise the traditional Indian model. Urbanisation, nuclear families, migration and changing employment patterns are reducing some traditional forms of family support.
Millions of young Indians now work hundreds or thousands of kilometres away from their parents. Women are increasingly financially independent. Young people are postponing marriage. Housing costs are rising in major cities. Healthcare expenses can be significant. Digital credit has made borrowing easier.
Consequently, the old assumption that “the family will take care of everything” is becoming less reliable. India therefore needs a hybrid wealth philosophy: traditional social capital + modern financial planning. That combination may be more relevant than blindly copying either model.
What Buffett actually teaches, and what India can adapt
Warren Buffett’s investment philosophy is often simplified into “buy good companies and hold them for the long term.” His own Berkshire Hathaway writings are considerably more nuanced. Buffett has repeatedly emphasised staying within one’s circle of competence, understanding businesses and thinking in long time horizons.
These are not exclusively American ideas. They are universal investment disciplines, and an Indian investor can absolutely learn from them. But implementation requires Indian adaptation. The Indian investor must consider:
- Indian taxation,
- Indian interest rates,
- domestic inflation,
- currency movements,
- family obligations,
- retirement requirements,
- Indian market valuations,
- regulatory conditions,
- and the individual’s capacity to tolerate losses.
Therefore, the lesson should not be “Do exactly what Buffett does.” It should be “Think patiently and understand what you own.” That distinction is enormous.
Kiyosaki’s message is more useful as a framework than as a prescription
Robert Kiyosaki’s philosophy emphasises financial education, cash flow, assets versus liabilities and independent financial decision-making. His Rich Dad materials present these as core foundations of financial literacy. Those concepts can be valuable for Indian households, but an Indian reader must translate them into local reality.
Kiyosaki’s simplified distinction between assets and liabilities is based on whether something puts money into or takes money out of one’s pocket. An Indian family, however, may deliberately purchase a house that produces no monthly income. Why? Because the house provides: security + shelter + social stability + protection from rent inflation + potential inheritance.
Financial accounting may not describe all of those benefits as investment returns. But family economics certainly recognises them. This is where a purely cash-flow-based definition of wealth becomes incomplete.
Is the family home an asset or a liability?
This question illustrates the difference beautifully. Suppose an Indian family buys a ₹1 crore home. The house generates no rent. It requires EMI, maintenance, property tax, repairs and other costs. Under Kiyosaki’s simplified cash-flow framework, it may resemble a liability.
But imagine the family remains there for 30 years. They avoid rent. The children grow up there. The parents have stability. The property eventually passes to the children. Its market value may also change over time. Was it merely a liability?
Clearly, the answer depends on the question being asked. As a cash-flow asset, perhaps not. As a housing asset, yes. As family security, certainly valuable. As an investment, its return must be separately calculated. This is why financial education must go beyond slogans.
India’s hidden wealth: social capital
There is another form of wealth that conventional Western financial spreadsheets struggle to capture: social capital. A trustworthy family doctor. A supportive extended family. A neighbour who helps during an emergency. A friend who provides professional advice. A relative who helps a young person find employment. A family network that supports children during difficult periods.
These relationships have economic value even though they do not appear on a balance sheet. India’s social structure has historically provided many such informal safety nets, but urbanisation is weakening some of them. Therefore, modern Indians may need to build both financial capital and social capital. One cannot always replace the other.
Gold tells an important Indian story
Why does gold occupy such a special place in Indian households? The answer is not simply investment return. Gold has historically represented security, liquidity, tradition, marriage, inheritance and emergency wealth.
For generations, Indian families have accumulated gold gradually. A grandmother’s jewellery becomes a daughter’s security. A daughter’s jewellery becomes part of the next generation’s inheritance. This is wealth transmission through culture.
Modern portfolio theory may classify gold differently, but Indian household psychology gives it a meaning that cannot be understood merely through a price chart. That does not mean every household should buy large quantities of gold. It means financial planning must understand why people hold it before telling them to stop holding it.
Wealth creation in India must include the next generation
Many Indians do not invest exclusively for themselves. They invest for “the family.” A parent may sacrifice consumption to educate a child. A family may build a house that will eventually be inherited. A business owner may create an enterprise intended to continue through generations. A farmer may invest in land knowing that children will eventually inherit it.
This is intergenerational wealth creation. Western financial literature often focuses heavily on individual financial independence. Indian financial thinking can legitimately include:
individual independence + family security + intergenerational continuity.
Neither model has to completely replace the other.
But tradition has a danger too
India should not glorify every traditional financial habit. Some traditional behaviours can also destroy wealth. Examples include:
- excessive investment in physical gold,
- concentrating wealth in one property,
- borrowing for social ceremonies,
- spending beyond income to maintain status,
- refusing to diversify,
- keeping excessive money idle,
- relying entirely on children for retirement,
- or allowing family pressure to dictate every financial decision.
Culture can protect wealth. Culture can also consume wealth. Therefore, the objective should not be to choose tradition versus modern finance. It should be: Preserve the wisdom. Remove the weaknesses.
India’s greatest financial asset may be its human capital
For a developing economy, the most important investment may not initially be stocks, property or gold. It may be skills. A young Indian who spends money acquiring a professional qualification, technology skill, language capability or entrepreneurial capability may increase lifetime earning capacity dramatically. That additional income can then be converted into financial assets. The sequence becomes:
Education → Skills → Income → Savings → Investment → Compounding → Intergenerational Wealth
This is particularly relevant in an economy experiencing technological transformation. AI may change jobs. Automation may eliminate some tasks. New industries will emerge. Therefore, financial freedom cannot be separated from employability.
The person who invests ₹10,000 in developing a skill that increases annual income by ₹2 lakh may have created more economic value than someone searching endlessly for an extra percentage point of investment return.
The Indian definition of financial freedom should be broader
Perhaps India needs its own financial-freedom equation:
Financial Freedom = Income Security + Emergency Reserves + Manageable Debt + Investment Assets + Health Protection + Family Security + Skills + Social Capital + Peace of Mind
Notice what is missing: “Maximum possible wealth.” Maximum wealth and maximum life satisfaction are not necessarily the same thing. A person can continue accumulating money indefinitely and still feel poor. Another person may reach a point where additional wealth adds little to happiness.
This is where Indian philosophical traditions offer an important counterweight to modern consumerism: how much is enough?
The psychology of “enough”
Modern consumer economies are exceptionally good at creating new wants. A bigger house. A bigger car. A better phone. A foreign holiday. A premium school. A luxury lifestyle. A second home. A larger portfolio. There is nothing inherently wrong with any of these. The problem begins when consumption becomes a permanent competition.
Indian philosophy has traditionally given considerable importance to restraint, contentment and balance. That does not mean poverty should be celebrated. It means wealth should serve life rather than life becoming permanently devoted to accumulating wealth. This distinction may become increasingly important in an age of social-media comparison.
India does not need less financial ambition
It needs smarter financial ambition. The new Indian wealth philosophy should encourage people to earn more, learn more, save intelligently, invest systematically, protect against catastrophic risks, avoid destructive debt, build businesses and assets, and still understand when enough is enough. That is not anti-capitalism. It is mature capitalism.
A financially educated Indian should be able to appreciate Buffett’s patience without becoming Buffett. Learn Kiyosaki’s cash-flow concepts without copying every strategy. Understand equity markets without making the stock market the centre of life. Own property without assuming every property automatically creates wealth. Hold gold without believing gold alone guarantees financial security. Build wealth without sacrificing family relationships.
The real lesson from Buffett and Kiyosaki
The irony is that the deeper lessons from these personalities may actually be more universal than their popular interpretations. Buffett’s message about staying within one’s circle of competence can be translated into: know what you understand. His emphasis on long-term thinking can become: do not allow short-term market emotions to dictate long-term decisions. Kiyosaki’s emphasis on financial education can become: understand your income, expenses, assets, liabilities and cash flows before investing.
Those principles are perfectly compatible with Indian conditions. What may not transfer directly are the specific strategies, assumptions and financial products surrounding them. That distinction is crucial.
India’s future wealth model may be a hybrid
India does not have to choose between the Western capitalist model and its traditional social philosophy. It can create something more suitable for its own circumstances.
Western financial discipline can provide investment knowledge, diversification, financial literacy, capital-market participation, entrepreneurship, risk management and long-term compounding.
Indian social philosophy can provide family responsibility, intergenerational thinking, moderation, social capital, community support, respect for education, dignity beyond material possessions, and the concept of “enough.”
Together they can create a more complete definition of wealth.
The new Indian wealth mantra
The Indian investor of the future should not ask only: “How much money can I make?” The better questions are:
- Can I protect my family?
- Can I survive a financial emergency?
- Can I educate my children without destroying my retirement?
- Can I support my parents without becoming financially vulnerable?
- Can my wealth survive me?
- Can I pass something meaningful to the next generation?
- Can I enjoy life while building wealth?
And ultimately, can my money give me freedom rather than becoming another source of anxiety? That is a much wider definition of financial freedom.
Conclusion: Wealth is not a number on a spreadsheet
The world will continue to celebrate Warren Buffett, Robert Kiyosaki and other financial personalities. And it should. Their ideas can provide valuable education. But India should not become a nation of financial imitators. India needs financially literate citizens capable of taking global principles and adapting them to local reality.
Our economic circumstances are changing rapidly. Our families are changing. Our cities are changing. Our technology is changing. Our aspirations are changing. But one thing remains important: money is a means. It is not the entire meaning of life.
For many Indians, real wealth is not simply a large bank balance. It is a secure home. Healthy parents. Educated children. A dignified retirement. Freedom from destructive debt. The ability to help someone in need. A business or profession that provides dignity. Assets that can support the next generation. Relationships that survive financial success. And finally, the peace of knowing:
“I have enough—not because I stopped dreaming, but because I learned what truly matters.”
Perhaps that is the financial philosophy India should carry into the next two decades: create wealth, protect wealth, transfer wealth, enjoy wealth, but never allow wealth to become the measure of your entire life.
Frequently Asked Questions
What is the Indian wealth philosophy?
It is a view of wealth that goes beyond net worth. It includes a home, children’s education, support for parents, gold, social relationships, health protection and peace of mind, alongside investments.
Can Western financial advice like Buffett and Kiyosaki be applied in India?
Their core ideas, such as patience, understanding what you own and financial education, are universal. Specific strategies must be adapted to Indian taxation, interest rates, inflation, family duties and products.
Is a family home an asset or a liability in India?
It depends on the question asked. As a cash-flow asset it may not qualify, but it provides shelter, security, protection from rent inflation and possible inheritance. Its investment return must be calculated separately.
What does financial freedom mean for an Indian family?
For many families it means having enough resources to fulfil responsibilities without becoming a burden on the next generation. It combines income security, emergency reserves, manageable debt, investments, health protection, skills, social capital and peace of mind.
Why is the idea of enough important in personal finance?
Maximum wealth and maximum life satisfaction are not the same. Knowing how much is enough helps wealth serve life, rather than life being spent only on accumulating wealth.
How much money is enough for financial freedom in India?
There is no single number. It depends on your family’s expenses, health cover, children’s education, parents’ support and lifestyle. A useful test is whether your income from investments and savings can cover these needs without forcing you to compromise your peace of mind.
What role does the family play in Indian wealth planning?
In most Indian households wealth is shared across generations. Parents are supported, children’s education and marriage are planned for, and property or gold is often passed on. This social capital is a real financial strength that Western models rarely count.
What does wealth mean for many Indian families beyond net worth?
The article says wealth often means owning a home, educating children, supporting parents, helping siblings, maintaining family dignity, possessing some gold, having social relationships, a stable career, the ability to face medical emergencies, supporting children’s marriages, leaving something for the next generation, contributing to society and having peace of mind. A person with Rs 5 crore may still feel insecure while another with a modest house and no major debt may consider himself wealthy.
Why is the Indian family called an economic institution?
According to the article, an individual’s financial decision frequently affects several generations: parents support children, children support parents, siblings help each other, family property stays within generations and gold may pass from grandmother to daughter to granddaughter. A planner who sees only an individual’s balance sheet may miss half the story, and for many Indians financial freedom means having enough to fulfil responsibilities without becoming a burden on the next generation.
What should an Indian investor consider when adapting global financial ideas?
The article lists Indian taxation, interest rates, domestic inflation, currency movements, family obligations, retirement requirements, market valuations, regulatory conditions and the individual’s capacity to tolerate losses. It says patience and financial education are universal ideas but their specific strategies must be fitted to Indian circumstances, with a hybrid model of traditional social capital and modern financial planning. This is general information, not investment advice.
Related Reading
- Why Buffett, Kiyosaki and other wealth-building philosophies cannot be applied blindly to ordinary people across the world
- The Hidden Cost of Living: How Psychological Management Can Change It
- Warren Buffett: The Psychology of Wealth
- Rich Dad Poor Dad: The Lessons the New Generation Must Learn Before Money Teaches Them the Hard Way
- The Psychology of Money: The Invisible Force That Drives Human Life
See more of our stories on Google Search
Leave a Reply