Repo Rate, Rupee, Inflation and the Common Man: The Hidden Psychology Behind India’s Next Monetary Policy Decision
From a 25-basis-point decision in Mumbai to the EMI of a middle-class family, the profitability of a factory, the value of the rupee and the purchasing power of an ordinary Indian — how one RBI decision can influence an entire economic ecosystem.
The RBI policy December 2026 decision is due on 4 December, following the Monetary Policy Committee meeting scheduled in the RBI’s published meeting calendar. In its October 2026 statement, the RBI raised the repo rate from 5.25% to 5.50%, so every borrower and saver is now watching what comes next. This guide explains how a repo rate move reaches your EMI, your fixed deposit and your household budget. If you want the basic chain first, read our 10-step guide to repo rate impact.
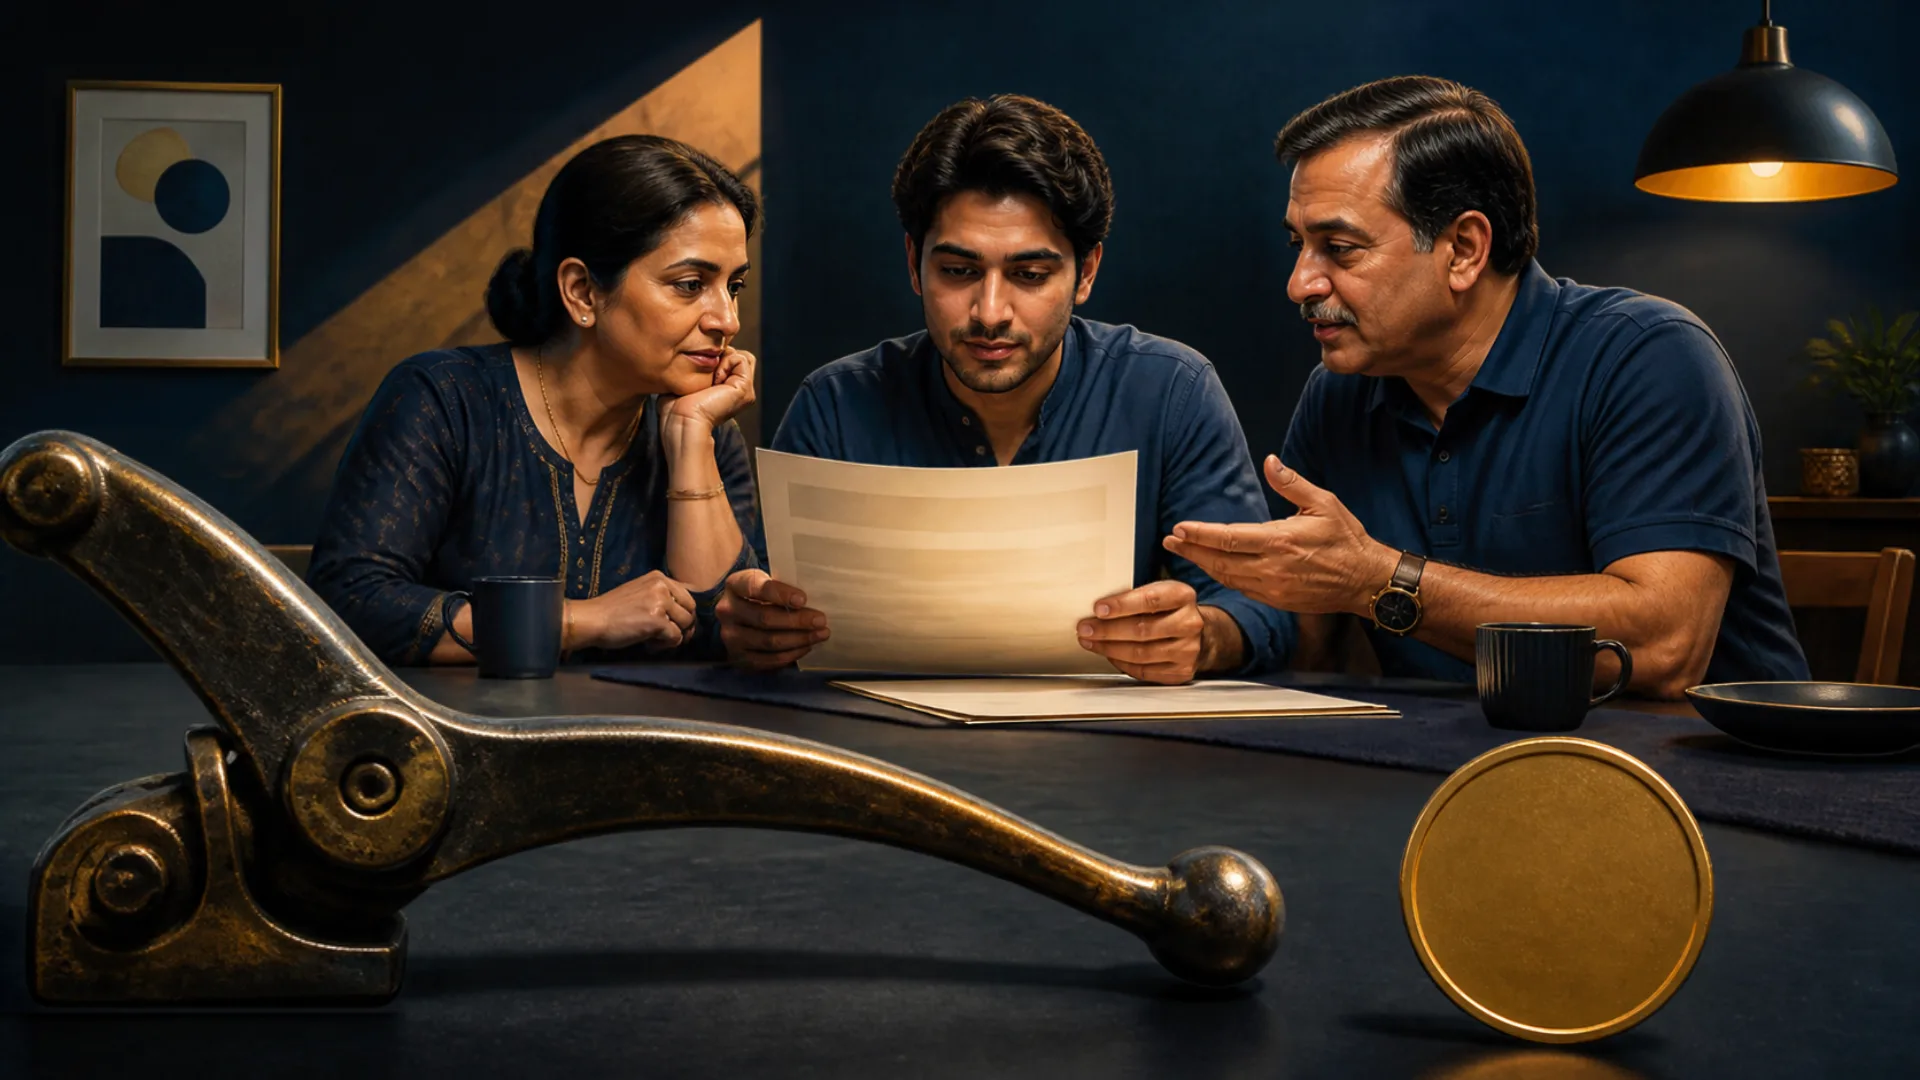
Imagine a middle-class family earning ₹80,000 every month.
The family has a home loan, a vehicle loan, children’s education expenses, insurance premiums and household expenditure. It is already managing its finances carefully.
Now imagine that the Reserve Bank of India increases the repo rate.
The family’s bank may eventually increase its lending rate. Its home-loan EMI may rise, or the repayment period may become longer. The family may postpone buying a car, reduce discretionary shopping and reconsider its holiday plans.
At the same time, a retired person with substantial fixed deposits may welcome the possibility of better interest income.
A businessman planning a new factory may postpone expansion, while an exporter earning dollars may benefit from rupee depreciation.
One monetary-policy decision. Different people. Different consequences. Different emotions.
This is the fascinating relationship between monetary policy and human psychology.
On December 2–4, 2026, the RBI’s Monetary Policy Committee (MPC) will meet to review India’s economic conditions and decide its next policy course. The announcement is expected on December 4.
The current repo rate is 5.50%, following the 25-basis-point increase in October 2026. The policy stance has also shifted from neutral to calibrated tightening.
The question confronting the RBI is difficult:
Should it tighten monetary conditions further to control inflation and protect economic stability, or should it pause to avoid putting additional pressure on consumption, investment and growth?
This decision is not confined to economists, bankers and financial-market participants.
It concerns every Indian household.
Key Takeaways
- The decision is on 4 December — the RBI raised the repo rate from 5.25% to 5.50% in October 2026, so the December outcome decides whether borrowing costs rise further, hold or ease.
- Your EMI reacts first — on a ₹50 lakh loan over 20 years, a rise from 8.5% to 8.75% adds roughly ₹795 a month (about ₹44,186 instead of ₹43,391).
- Prepare, do not predict — keep an emergency fund, avoid new high-cost debt and review your loan and deposit rates instead of guessing the RBI’s move.
Updated 2 November 2026. This article is general information, not investment or financial advice. Loan and deposit rates vary by bank, so check your own loan agreement and your bank’s current rates.
Table of Contents
- 1. REPO RATE: THE PRICE OF MONEY AND THE RBI’S ECONOMIC BRAKE
- 2. WHY THE RBI POLICY DECEMBER 2026 MEETING IS PARTICULARLY IMPORTANT
- 3. THE PSYCHOLOGICAL FACTOR: EXPECTATIONS CAN CHANGE THE ECONOMY BEFORE THE EMI CHANGES
- 4. PURCHASING POWER: THE REAL BATTLE IS INSIDE THE HOUSEHOLD BUDGET
- 5. EMI: THE MOST VISIBLE CONNECTION BETWEEN RBI AND THE COMMON MAN
- 6. PRICES AND DEMAND: WILL A RATE HIKE MAKE GOODS CHEAPER?
- 7. RUPEE VERSUS DOLLAR: WHY THE CURRENCY MARKET MATTERS TO EVERY INDIAN
- 8. IMPORTS AND EXPORTS: TWO SIDES OF THE SAME CURRENCY MOVEMENT
- 9. FOREIGN-EXCHANGE RESERVES: INDIA’S FINANCIAL SHIELD
- 10. CORPORATE PROFITABILITY: WHEN THE COST OF MONEY REACHES THE FACTORY FLOOR
- 11. THE SAVER’S PSYCHOLOGY: WHEN HIGHER RATES BRING RELIEF
- 12. STOCK MARKETS: WHY INVESTORS REACT BEFORE THE ECONOMY DOES
- 13. THE DECEMBER DECISION: THREE POSSIBLE DIRECTIONS
- 14. WHAT SHOULD AN ORDINARY INDIAN FAMILY DO?
- 15. THE BIGGER QUESTION: WHAT DOES A HEALTHY ECONOMY REALLY LOOK LIKE?
- 16. THE FINAL MESSAGE: RBI DECIDES THE RATE, BUT PEOPLE DECIDE THE ECONOMIC RESPONSE
- Frequently Asked Questions
1. REPO RATE: THE PRICE OF MONEY AND THE RBI’S ECONOMIC BRAKE
The repo rate is the rate at which the RBI lends short-term funds to eligible banks against securities under the liquidity adjustment facility.
It is one of the most important instruments of monetary policy.
Think of the economy as a vehicle.
When inflation becomes excessive, RBI can apply the monetary-policy brake by increasing interest rates.
When economic activity becomes weak and inflation permits, it can reduce interest rates to encourage borrowing, consumption and investment.
The objective is to maintain a reasonable balance between:
- Economic growth
- Inflation control
- Financial stability
- Credit availability
- Currency stability
- Sustainable consumption and investment
But the repo rate is not a magic switch.
It influences the financial environment through banks, financial markets, borrowers, investors and businesses.
The RBI changes the price of money; the economy responds through millions of financial decisions.
2. WHY THE RBI POLICY DECEMBER 2026 MEETING IS PARTICULARLY IMPORTANT
The October 2026 policy decision has changed the monetary-policy environment.
The RBI increased the repo rate from 5.25% to 5.50% and adopted calibrated tightening.
The October MPC minutes indicated that rate cuts were off the table in the near term, with future action depending on inflation, underlying price pressures and economic growth.
The RBI’s October assessment also projected FY2027 real GDP growth at 7.1% and CPI inflation at 5.2%.
The challenge is that India’s growth remains resilient while inflationary risks have increased.
The international environment is equally complicated:
- Geopolitical tensions in West Asia.
- Volatile international crude oil prices.
- Higher global interest rates and bond yields.
- Pressure on emerging-market currencies.
- Foreign portfolio investment movements.
- Uncertainty in international trade and supply chains.
The December meeting will therefore be an important test of the RBI’s assessment of the balance between growth and inflation.
A pause would not necessarily mean that inflation risks have disappeared. Another hike would not necessarily mean that the economy is weak.
The RBI has to evaluate the direction of the economy rather than react to one isolated indicator.
3. THE PSYCHOLOGICAL FACTOR: EXPECTATIONS CAN CHANGE THE ECONOMY BEFORE THE EMI CHANGES
One of the most interesting aspects of monetary policy is human psychology.
Suppose a borrower hears that interest rates may rise further.
Even before the bank revises the loan rate, the borrower may start postponing major purchases.
A businessman may delay a new investment.
A property buyer may wait for clarity.
A household may start saving more.
An investor may become cautious.
This is the expectations channel of monetary policy.
Economic decisions are often influenced not only by present financial conditions but also by expectations about tomorrow.
The reverse is equally true.
When people believe inflation will remain high, they may purchase goods earlier, demand higher salaries or increase prices in anticipation of future costs.
Such behaviour can make inflation more persistent.
Therefore, central banks must manage not only the availability and cost of money but also public confidence in the future value of money.
4. PURCHASING POWER: THE REAL BATTLE IS INSIDE THE HOUSEHOLD BUDGET
Inflation is not merely an economic statistic.
It is a reduction in the purchasing power of household income.
A salary of ₹50,000 may remain unchanged, but if food, electricity, transportation, education and healthcare become more expensive, the family gradually loses its financial comfort.
A repo-rate increase creates two opposing effects.
For borrowers:
Higher borrowing costs can reduce disposable income and purchasing power.
For the overall economy:
If higher rates moderate excessive demand and inflation over time, they can help protect the purchasing power of the rupee.
This is the difficult paradox of monetary policy.
A policy that creates short-term financial discomfort may be intended to protect consumers from a more damaging and persistent inflation problem.
However, interest-rate increases cannot directly solve every price problem.
If vegetable prices rise because of crop damage, or crude oil becomes expensive because of geopolitical conflict, the RBI cannot immediately increase supply.
Its role is principally to prevent temporary price shocks from spreading into generalised inflation and inflation expectations.
5. EMI: THE MOST VISIBLE CONNECTION BETWEEN RBI AND THE COMMON MAN
Before reading the worked example below, it helps to know your own ratio: see how much of your salary should go to EMI.
For millions of Indian families, the repo rate becomes meaningful when it reaches their home-loan statement.
Consider an illustrative ₹50 lakh home loan for 20 years at 8.5% interest.
The approximate EMI is ₹43,391.
If the interest rate increases to 8.75%, the EMI becomes approximately ₹44,186, assuming the original tenure remains unchanged.
That is an additional monthly burden of approximately ₹795.
The actual change depends on the loan benchmark, bank spread, reset frequency and repayment structure. A bank may also retain the EMI and extend the tenure.
The larger concern is the cumulative burden on families already managing several loans.
A family carrying a home loan, car loan, personal loan and credit-card dues has less financial flexibility.
The psychological impact can be even greater than the immediate monetary impact.
People begin worrying about:
- Job security.
- Children’s education.
- Medical emergencies.
- Future interest-rate changes.
- Their ability to maintain their existing lifestyle.
This is why responsible borrowing is as important as access to credit.
A loan should be taken according to repayment capacity, not according to the maximum amount a bank is willing to offer.
6. PRICES AND DEMAND: WILL A RATE HIKE MAKE GOODS CHEAPER?
Rate decisions work on inflation slowly, while your grocery bill moves every week. Our note on India’s silent inflation shows where household costs hide.
A repo-rate increase does not automatically reduce the price of petrol, vegetables, medicines or household essentials.
Its influence is more indirect.
Higher interest rates can make borrowing expensive, reduce excessive consumption and moderate demand for certain goods and services.
Businesses may reconsider expansion and inventory purchases.
Consumers may postpone discretionary expenditure.
Eventually, if demand pressure moderates, businesses may find it more difficult to increase prices.
However, there is a significant distinction between demand-driven and supply-driven inflation.
Demand-driven inflation: Monetary tightening can help.
Supply-driven inflation: Interest rates alone cannot solve it.
For example, if transportation costs rise because international crude becomes expensive, the cost of moving vegetables, medicines and manufactured goods can increase.
The RBI cannot eliminate that cost simply by increasing the repo rate.
The government must complement monetary policy with appropriate supply-side measures.
7. RUPEE VERSUS DOLLAR: WHY THE CURRENCY MARKET MATTERS TO EVERY INDIAN
The exchange rate is another important dimension of the December policy decision.
A weaker rupee makes imported goods and raw materials more expensive.
India imports substantial quantities of crude oil, electronics, machinery, chemicals and other industrial inputs.
When the rupee depreciates, the same dollar-denominated import requires more rupees.
For example:
- At ₹80 per dollar, a $1 million import costs ₹8 crore.
- At ₹95 per dollar, the same import costs ₹9.5 crore.
The difference is ₹1.5 crore, even though the dollar price has not changed.
This additional cost can eventually travel through the supply chain.
It may affect fuel, transportation, aviation, industrial production, packaging and consumer prices.
A higher domestic interest rate can potentially make Indian financial assets more attractive relative to overseas alternatives and support the rupee.
But this relationship is not automatic.
The rupee is also influenced by US interest rates, global dollar strength, crude oil prices, foreign investment, trade flows and geopolitical developments.
The currency market cannot be controlled by the repo rate alone.
8. IMPORTS AND EXPORTS: TWO SIDES OF THE SAME CURRENCY MOVEMENT
A weaker rupee can create opportunities for exporters.
An Indian company earning dollars may receive more rupees when converting its foreign earnings.
Sectors such as IT services, pharmaceuticals, textiles and engineering exports may benefit, depending on their cost structures and international contracts.
But import-dependent exporters may also face higher costs for machinery, components, energy and raw materials.
For importers, the situation is more difficult.
A weaker rupee can increase the cost of imported goods and reduce profit margins.
For India, this becomes particularly important because a higher oil import bill can widen the trade deficit and put additional pressure on the external account.
Therefore, a weaker rupee is neither automatically good nor automatically bad.
The real question is whether the benefit to export competitiveness is greater than the additional cost of imported inputs.
9. FOREIGN-EXCHANGE RESERVES: INDIA’S FINANCIAL SHIELD
India’s reserves were reported at about $719.75 billion in the latest weekly data, a fall of $1.27 billion, as Business Standard reported.
Foreign-exchange reserves provide an important cushion against external economic shocks.
They help the country meet international payment obligations and give the RBI the ability to manage excessive volatility in the foreign-exchange market.
Recent developments deserve attention.
India’s foreign-exchange reserves declined to approximately $719.75 billion in the week ended October 23, 2026, according to the latest reported data available at the beginning of November.
This was the seventh consecutive weekly decline.
However, the decline should not be interpreted simply as dollars being spent to defend the rupee.
Reserve movements also reflect changes in gold valuations, foreign-currency asset values, intervention and other balance-sheet movements.
India continues to possess a substantial reserve buffer.
The important issue is maintaining adequate reserves while allowing the currency to adjust to changing global conditions.
A central bank cannot indefinitely defend an artificial exchange-rate level at any cost.
Currency confidence ultimately depends on economic fundamentals, not merely on intervention.
10. CORPORATE PROFITABILITY: WHEN THE COST OF MONEY REACHES THE FACTORY FLOOR
Corporate India is directly connected to monetary policy.
Consider a manufacturing company planning to establish a new factory.
It needs money for:
- Land and buildings.
- Machinery.
- Raw materials.
- Employees.
- Transportation.
- Working capital.
If borrowing becomes expensive, the company’s financial calculations change.
Higher finance costs can reduce net profit.
If consumers also reduce purchases, revenue growth may slow.
The company may postpone expansion, reduce inventory or delay recruitment.
Interest-sensitive industries such as real estate, automobiles, construction and consumer durables can be particularly affected.
However, companies with low debt, strong cash flows, pricing power or export earnings may be better positioned.
For banks, the impact depends on the relationship between lending rates, deposit rates, funding costs, margins and asset quality.
The important lesson is that corporate profitability depends not merely on sales but also on the cost of capital.
11. THE SAVER’S PSYCHOLOGY: WHEN HIGHER RATES BRING RELIEF
Monetary policy does not benefit or hurt everyone equally.
Consider a retired person who has accumulated ₹30 lakh in fixed deposits.
A higher deposit rate may improve the person’s interest income.
For a conservative saver, this can provide psychological comfort.
The same rate increase that worries a home-loan borrower may encourage a retired person to invest in interest-bearing deposits.
But savers should also consider taxation, inflation, deposit tenure, liquidity and the safety of the institution.
A higher nominal interest rate does not automatically mean a higher real return.
The real return is what remains after accounting for inflation and taxes.
The economy needs a balance between borrowing for productive purposes and disciplined saving for future security.
12. STOCK MARKETS: WHY INVESTORS REACT BEFORE THE ECONOMY DOES
Financial markets are forward-looking.
Investors continuously assess what may happen to corporate profits, interest rates, currency movements and economic growth.
A higher repo rate may reduce the attractiveness of some equity valuations because investors can obtain better returns from relatively safer interest-bearing assets.
It may also increase corporate borrowing costs.
Foreign investors compare Indian investment opportunities with returns available in the United States and other markets.
A stronger dollar or higher US bond yields can encourage capital to move towards dollar-denominated investments.
But markets do not respond to the repo rate alone.
They respond to the entire economic narrative.
That is why the RBI’s language, inflation projections and policy guidance can sometimes influence markets more than the actual 25-basis-point change.
13. THE DECEMBER DECISION: THREE POSSIBLE DIRECTIONS
The December meeting should be viewed through three possible scenarios rather than assumptions about a guaranteed rate increase.
Scenario A: RBI maintains the repo rate at 5.50%.
This could indicate that the October increase is considered sufficient for the time being, provided inflation expectations and underlying price pressures remain manageable.
The RBI could continue calibrated tightening while waiting for more economic data.
Scenario B: RBI increases the repo rate further.
This could happen if inflation becomes more persistent, the impact of higher energy costs spreads across the economy or inflation expectations become difficult to control.
The immediate consequences could include additional pressure on floating-rate borrowers, tighter financial conditions and greater caution among businesses.
Scenario C: RBI changes its policy assessment.
If growth weakens significantly or inflation risks moderate, the MPC could reconsider its approach.
However, a shift towards rate cuts would require a change in the economic outlook and policy assessment. It should not be assumed merely because businesses or borrowers want cheaper money.
The actual decision will depend on the evidence available to the MPC in December.
14. WHAT SHOULD AN ORDINARY INDIAN FAMILY DO?
Whatever the RBI decides, avoid borrowing on impulse; our guide to the easy credit trap lists nine rules that protect you.
Monetary policy is not within the control of an ordinary household.
But household financial behaviour is.
A few practical steps can reduce vulnerability.
- Review floating-rate loans: Understand the benchmark, interest spread and reset frequency.
- Avoid unnecessary borrowing: Do not take a loan simply because a bank or fintech company offers it.
- Build emergency savings: Maintain a reasonable reserve for essential expenses and unexpected job or medical problems.
- Control credit-card debt: Avoid revolving balances and expensive short-term borrowing.
- Reassess major purchases: Separate genuine needs from lifestyle pressure and social competition.
- Compare deposit options: Evaluate interest rates, taxation, liquidity and institutional safety.
- Avoid emotional investment decisions: Do not panic-sell investments simply because the RBI increases interest rates.
- Businesses should calculate debt capacity: Expansion should be based on realistic cash flows, not optimistic sales projections.
One principle should guide every household:
Financial eligibility is not financial affordability.
15. THE BIGGER QUESTION: WHAT DOES A HEALTHY ECONOMY REALLY LOOK LIKE?
A healthy economy is not one where interest rates are always low, stock markets always rise or the rupee never depreciates.
A healthy economy should have:
- Sustainable GDP growth.
- Manageable inflation.
- Productive employment.
- Financially stable households.
- Responsible corporate borrowing.
- Strong banking institutions.
- Healthy domestic investment.
- Adequate foreign-exchange reserves.
- Competitive exports.
- Sustainable external balances.
India needs economic growth, but growth based entirely on excessive borrowing and consumption cannot remain sustainable indefinitely.
Similarly, inflation control should not come at the cost of unnecessarily suppressing productive investment and employment.
The real objective is balanced economic development.
16. THE FINAL MESSAGE: RBI DECIDES THE RATE, BUT PEOPLE DECIDE THE ECONOMIC RESPONSE
The December 4 monetary-policy announcement will be closely watched by banks, businesses, investors, exporters, importers and millions of borrowers.
But the most important story will be what happens after the announcement.
A family may reconsider a home purchase.
A young professional may postpone a vehicle loan.
A businessman may delay a factory.
A retired person may reconsider fixed deposits.
An importer may hedge dollar exposure.
An exporter may reassess international pricing.
A bank may review its lending strategy.
These decisions, repeated across millions of households and businesses, influence the economic direction of the country.
The RBI cannot control every international event, manufacture crude oil, guarantee rainfall or dictate the global dollar market.
What it can do is influence the financial conditions in which economic decisions are made.
And that is the real power of monetary policy.
A 25-basis-point change may look small on paper, but its consequences can travel through the financial lives of millions of people.
The repo rate is not merely a number announced from the RBI headquarters.
It is connected to the salary account, home loan, fixed deposit, business investment, grocery bill, stock portfolio and future financial security of ordinary Indians.
As India approaches December 4, the real question is not simply whether RBI will increase, maintain or reduce the repo rate.
The real question is whether India can maintain the delicate balance between affordable money, stable prices, productive investment and sustainable growth.
Because an economy is not healthy merely when its numbers look impressive.
An economy is truly healthy when its growth creates confidence, its currency retains credibility, its businesses remain productive and its ordinary citizens can live with financial dignity.
The RBI controls the monetary-policy lever. The banking system transmits it. Businesses and investors respond to it. But ultimately, its impact is experienced by millions of Indian families.
The price of money changes. The psychology of people changes. And through their collective decisions, the direction of the economy changes.
Frequently Asked Questions
When is the RBI policy decision in December 2026?
The RBI’s published schedule points to the decision being announced on 4 December 2026 after the Monetary Policy Committee meeting. Check the RBI website for the final confirmation.
What is the current repo rate?
In October 2026 the RBI raised the repo rate from 5.25% to 5.50%. The December decision will either change, or hold, that level.
What is the repo rate in simple words?
It is the rate at which the RBI lends short-term money to banks. A higher repo rate generally makes borrowing costlier across the banking system, and a lower rate makes it cheaper.
Will my home loan EMI rise if the RBI raises the repo rate?
If your floating-rate loan is linked to an external benchmark such as the repo rate, the rate usually resets as per your loan agreement, and the EMI or tenure can change. A fixed-rate loan does not change during its fixed period. Check your sanction letter.
How much more EMI will I pay if the rate rises by 0.25%?
On a ₹50 lakh loan over 20 years, a rise from 8.5% to 8.75% takes the EMI from about ₹43,391 to about ₹44,186, an increase of roughly ₹795 a month. Your actual change depends on your bank, spread and remaining tenure.
Do fixed deposit rates go up when the repo rate goes up?
Often over time, but banks decide their own deposit rates and the change is neither automatic nor equal. Compare the rates of different banks before booking a deposit.
Should I prepay my loan before the RBI decision?
There is no single answer. Compare your loan rate with the return on your safe savings, keep an emergency fund first, and check prepayment rules. Decide on your own numbers, not on a guess about the RBI.
How does the repo rate affect the rupee?
Higher interest rates can make a country’s assets more attractive to foreign investors and support its currency, but oil prices, global markets and capital flows also matter. The effect is not guaranteed.
How do rate decisions affect the stock market?
Markets react to expectations. A surprise relative to what investors expected usually moves prices more than the decision itself. This article is general information and not advice to buy or sell any security.
What should an ordinary family do before 4 December?
Build or top up an emergency fund, avoid new high-cost debt, check whether your loan is floating or fixed, and plan your budget for a small rise in EMI. Prepare for every outcome rather than predicting one.
Related Reading
- RBI Digital Lending Guidelines 2025: 9 Fixes Still Needed
- Gen Z Debt in India: 5 Warning Signs and How to Get Out
- Loan Against Property Interest Rate, Eligibility and Risks
- Gold Loan Auction Process: RBI Rules You Should Know
- Bank Strike in India: Will Banking Stop? What Still Works
See more of our stories on Google Search
Leave a Reply